
The Best Lenders for Bad Credit Loans in Arizona: 2026 Top 5 Picks
The Best Lenders for Bad Credit Loans in Arizona: 2026 Top 5 Picks
Last updated: 2026-10-16
Surviving the Arizona heat is one thing, but facing a mountain of unexpected debt is a whole different beast. For many residents, a sudden dental emergency or a broken AC unit in the middle of a Phoenix summer can throw your entire budget into chaos. When your credit score isn’t exactly perfect, finding a lender that looks at your actual situation rather than just a number is essential.
Picking a lender involves more than just glancing at a single interest rate. You have to weigh how fast you get the cash against how much that debt will cost you over time. A low rate sounds great, but if the repayment period is too short, those monthly payments might squeeze your budget tight. On the flip side, a long-term loan might keep payments low but end up costing you thousands extra in total interest.
This list helps Arizona residents find quick relief without falling into predatory traps. We focused on lenders that provide real options for those in a tight spot. Whether you need to fix a car to get to work or cover an urgent repair, the speed of funding can change your financial trajectory.
- LendingPoint
- OneAZ Credit Union
- Arizona Zip Loan
- AmeriCash Loans
- Allegiance Credit Union
Evaluating Financial Options Across the Grand Canyon State
We built this list by looking at how accessible different lending models are for people with less-than-perfect credit. Speed was a major factor. In a state where life moves fast, waiting two weeks for cash isn’t a realistic option. If your car is your only way to get to your job, a three-day delay in funding could mean lost wages or even losing your position entirely.
Transparency matters just as much as the interest rate. A lender might promise a low rate, but if they require a pristine 750 credit score, that rate is essentially a ghost. We looked at the gap between traditional banks, which often demand mountains of paperwork and in-person visits, and digital lenders that process everything on a smartphone in minutes.
The following table gives you a quick look at how these top contenders stack up against each other regarding amounts and speed.
| Lender Name | Loan Amount Range | Funding Speed | Credit Requirements |
|---|---|---|---|
| LendingPoint | $1,000 – $36,500 | See site | See site |
| OneAZ Credit Union | See site | See site | See site |
| Arizona Zip Loan | $1,000 – $35,000 | 24hrs | See site |
| AmeriCash Loans | See site | Instant decision | Good credit not needed |
| Allegiance Credit Union | See site | See site | See site |
Top Rated Lenders for Arizona Residents
1. LendingPoint
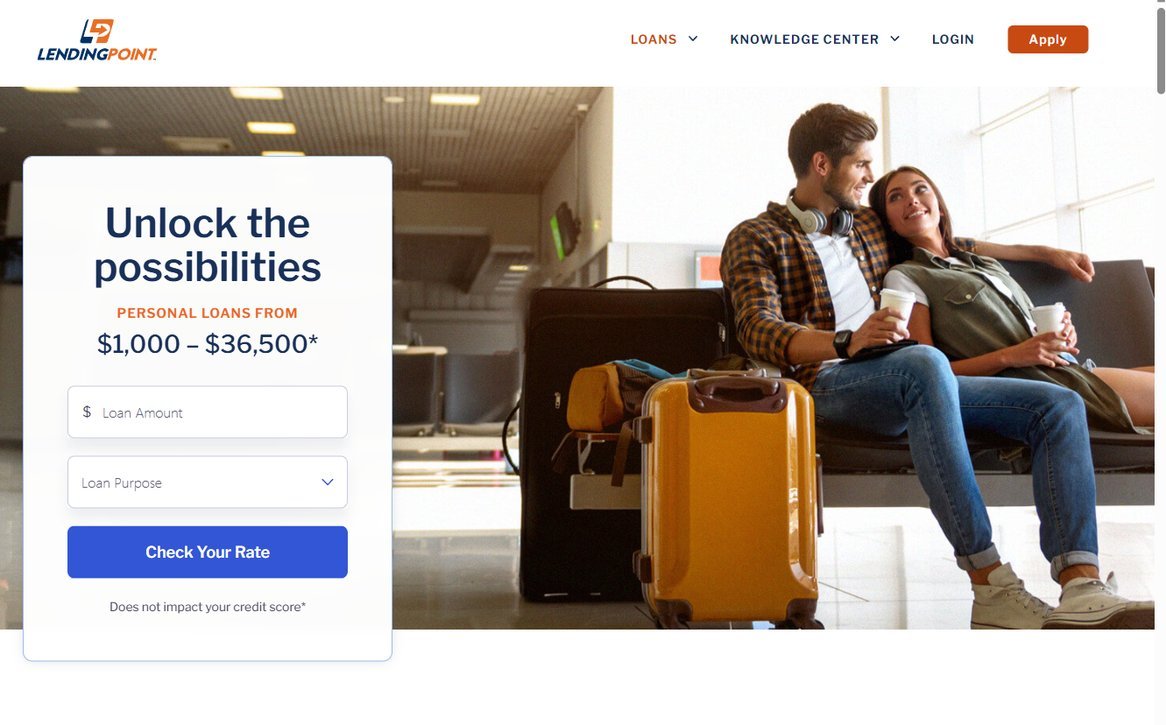
LendingPoint works well for people needing a significant chunk of cash for major life events. Whether you are planning a wedding or trying to consolidate a mountain of credit card debt, their platform handles a variety of needs. They offer different loan purposes to fit almost any financial emergency that pops up.
Since they handle larger sums, they are a popular choice for debt consolidation. This allows you to roll high-interest balances into a single, more manageable monthly payment. It can be a much simpler way to manage your monthly budget.
This lender is a good option if you want to check your eligibility without hurting your credit score. They use a soft credit pull for the initial quote. This means you can see your estimated rate and terms without any impact on your score before you commit to a formal application.
Pros:
- Flexible loan purposes including debt consolidation and travel.
- Check rates without impacting your credit score.
- High maximum loan amount of $36,500.
Cons:
- Specific eligibility requirements may vary.
2. OneAZ Credit Union
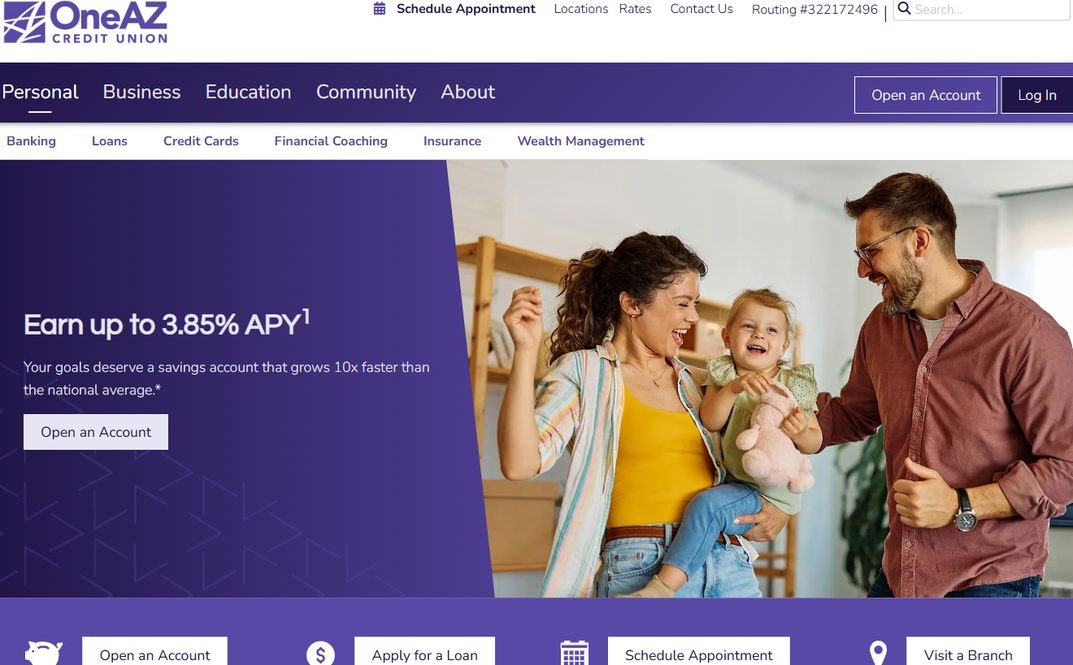
OneAZ Credit Union operates with a community-focused mindset that you rarely see at big corporate banks. They tend to focus on helping members reach long-term goals rather than just providing a quick fix. This makes them a solid choice if you want to build a real relationship with your lender.
Because credit unions are member-owned, their primary goal is to serve the community instead of maximizing shareholder profits. Unlike large national banks that treat you like a number on a spreadsheet, OneAZ offers a more personal touch. You might even find better service because they actually want you to succeed.
If you need more than just a one-time loan, they offer wealth management, mortgages, and financial coaching. It is a holistic approach that can help you move from just surviving to finding actual stability. They can help you create a savings plan so the next car repair doesn’t require a loan at all.
Pros:
- Comprehensive financial services and coaching.
- Potential for higher savings growth compared to national averages.
- Community-oriented membership benefits.
Cons:
- Membership requirements may apply.
3. Arizona Zip Loan
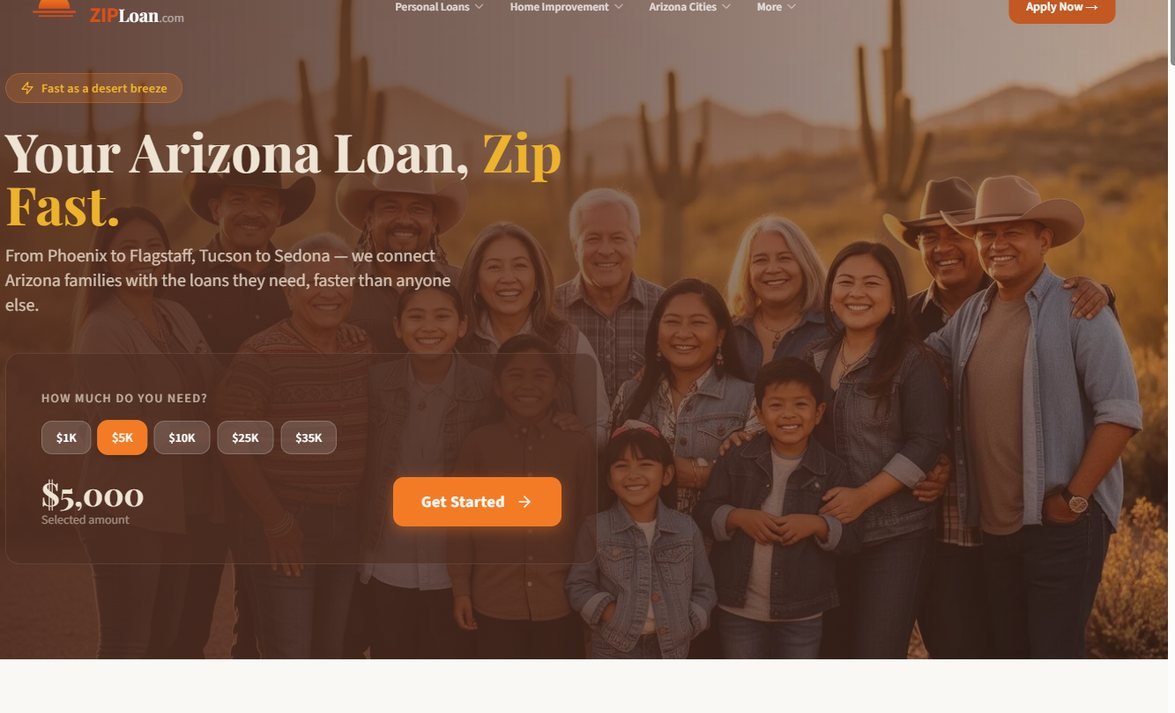
Speed is everything when you are dealing with an urgent crisis in Phoenix or Tucson. Arizona Zip Loan aims for an average approval time of just 24 hours. This is perfect for those facing immediate problems, like a broken water heater or a medical bill that needs to be paid right away.
They cater specifically to Arizona families, which gives them a localized feel that national websites often lack. Because they are rooted in the state, they understand the local economic reality. Their service is built to connect people with funds quickly and securely, closing the gap between an emergency and a solution.
Pros:
- Fast 24-hour average approval time.
- High customer rating of 4.9 stars.
- Wide geographic coverage across Arizona cities.
Cons:
- Strictly focused on personal loan structures.
4. AmeriCash Loans
AmeriCash Loans is built for anyone needing momentum right now. Their marketplace model connects you with lenders who are willing to look past a low credit score. It is a streamlined, digital-first approach for people in a rush who don’t want to waste time.
The application is incredibly straightforward. You only need to fill out a simple form to get things moving. You won’t find yourself stuck in complex menus or waiting on hold for an hour just to see if you qualify. It is a fast way to bridge a short-term cash gap.
This model is particularly helpful if you have a limited credit history or if a recent life event caused a temporary dip in your score. It removes the heavy lifting of contacting dozens of different lenders yourself.
Pros:
- Good credit is not a requirement for the marketplace.
- Fast application and instant decision process.
- Simple, secure digital interface.
Cons:
- Final terms are determined by third-party lenders.
5. Allegiance Credit Union
Allegiance Credit Union takes a very human approach to lending. They believe every financial story matters, whether you are buying your first home or rebuilding after a setback. This empathetic stance is a relief for those feeling discouraged by their credit history.
They understand that life is unpredictable and a temporary setback doesn’t have to define your entire financial future. They focus on supporting your well-being through various products. This is a lender for the long haul, helping you borrow smarter over time.
The goal is often to move you toward independence rather than just providing a temporary patch. This is helpful for people looking to graduate from small, high-interest loans to more stable credit lines as their financial health improves.
Pros:
- Mission-driven focus on financial well-being.
- Supportive environment for rebuilding credit.
- Variety of products for different life stages.
Cons:
- Geographic availability may be limited to specific regions.
Understanding the True Cost of Borrowing
Before you sign anything, remember that not all money is created equal. It is easy to get excited about an instant approval, but you must look at the total cost. When comparing two lenders, don’t just look at the interest rate. Look at the total amount you will have paid back by the time the loan is finished.
A 10% interest rate over 60 months is vastly more expensive than a 15% interest rate over 24 months. Always ask for the APR (Annual Percentage Rate) to see the true cost. The APR includes the interest rate plus mandatory fees, like origination or processing costs, which can drive up the actual price of the money.
If you borrow $5,000 but the lender charges a $300 origination fee, you only receive $4,700. However, you are still paying interest on the full $5,000. Understanding this simple math is your first line of defense against expensive debt.
How to Prepare for a Successful Loan Application
To increase your chances of approval and get the lowest rate, you need to be prepared. Even if your credit isn’t perfect, presenting yourself as a responsible borrower makes a difference to lenders. Follow these steps to get ready:
- Gather Documentation Early: Most lenders will want proof of identity, income, and residence. Have digital copies of your driver’s license, recent pay stubs, and a utility bill ready to upload to speed things up.
- Review Your Credit Report: You should know exactly what a lender sees. Check for errors or fraudulent activity that might be dragging your score down. Fixing a single mistaken late payment can sometimes jump your score enough to get a better rate.
- Calculate Your Debt-to-Income (DTI) Ratio: Lenders want to know if you can actually afford more debt. Divide your monthly debt payments by your gross monthly income. A lower ratio makes you a much more attractive candidate.
- Identify Your Specific Need: Be ready to explain exactly why you need the funds. Lenders are more comfortable when the purpose is clear and constructive, like home improvement or debt consolidation.
Avoiding Common Pitfalls in the Lending Process
Avoid the «quick fix» mentality. While a payday loan might solve a problem today, it can create a much larger crisis tomorrow if you aren’t careful. These loans often have extremely high interest rates and short repayment windows. This can force you into a cycle of taking new loans just to pay off old ones.
Make sure your monthly repayment fits comfortably within your existing budget. This prevents a debt cycle that feels impossible to escape. If the payment is a struggle every month, the loan is too big.
Lastly, verify that any lender reaching out is legitimate. Stick to well-known institutions or established marketplaces. Scams are common, especially when people are searching for quick cash. If a deal seems too good to be true, or if they demand upfront fees before releasing your funds, walk away. Legitimate lenders typically take their fees from the loan proceeds themselves.
Buy a bonus features let a player pay a fixed multiple of their stake to jump straight into a free spins round. It removes the wait, and it also removes any chance of the round arriving cheaply. The trade is entirely about cost against expected return.
Paying to Enter the Free Spins Round
Buying the round condenses hours of base play into one transaction, which magnifies both outcomes. Anyone checking where the feature is offered can Lizaro and see it flagged in game listings. Several regulators, including those in the United Kingdom and parts of Europe, restrict or ban the mechanic outright on consumer protection grounds.
| Buy Type | Typical Cost | Return Band |
|---|---|---|
| Standard bonus | 80x stake | 94% to 96% |
| Enhanced bonus | 200x stake | 95% to 96% |
| Feature spin | 5x stake | 94% to 96% |
- Note that buy prices vary widely for similar rounds
- Bankroll drains far faster with repeated purchases
The feature is a convenience, not an advantage, and its pricing reflects that carefully. Repeated purchases compress a long session into a handful of expensive bets. If a game offers it, decide beforehand how many buys a budget covers, and accept that the house edge applies to every one of them.
About Post Author

