
Top 5 Lenders for a 12 Year Personal Loan in 2026
Top 5 Lenders for a 12 Year Personal Loan in 2026
Last updated: 2026-10-16
Signing a long-term loan is a lot like a marriage contract with your bank. You are committing to a specific rhythm of payments that could span over a decade. This level of commitment requires a careful look at how interest compounds. You also need to consider how much freedom you require if your financial situation shifts unexpectedly.
When you extend a loan’s duration, you aren’t just stretching out the monthly obligation. You are fundamentally altering the mathematical relationship between your principal and the interest accrued. A small difference in the annual percentage rate (APR) might seem negligible over twelve months. However, when compounded over a decade, that difference can equate to thousands of dollars in additional cost.
Finding the right lender for a twelve-year term isn’t just about the lowest number on the screen. It is about finding a partner that offers stability and transparency. You want a path toward debt freedom rather than a mountain of interest. A lender might offer a low introductory rate that jumps significantly after two years. They might also bury prepayment penalties in the fine print that make it prohibitively expensive to refinance later. The following list highlights the top contenders available in the current market, evaluated for their reliability, product depth, and suitability for long-term commitments.
- JetzLoan
- Citi
- Alliant Credit Union
- MedLoan Finance
- United Bank
How These Lenders Were Evaluated
The selection process focused heavily on the availability of extended repayment terms. While many lenders stop at five or seven years, a true long-term option must allow for the extended flexibility required by larger debt consolidation projects or major life milestones. We looked for those who actually provide the runway necessary for a twelve-year horizon.
We scrutinized the amortization schedules to see how quickly the principal is actually being reduced in the early years of the term. A loan with a very slow principal reduction phase can leave you «underwater» if you try to sell an asset or refinance the debt halfway through the term. This is a trap many borrowers fall into without realizing it.
Beyond the duration, the comparison looked at the speed of funding and the ease of the application process. Lenders that offer a «soft» check to see rates without hurting your credit score were prioritized. This «pre-qualification» step is vital for modern consumers who want to shop around without triggering a hard inquiry on their credit report every time they want to see a hypothetical rate. We also considered the diversity of their product offerings to ensure they could serve users with varying credit profiles, from those with stellar 800+ scores to those rebuilding after a period of financial hardship.
| Lender Name | Loan Amounts | Max Term | Funding Speed | Credit Requirements |
|---|---|---|---|---|
| JetzLoan | $500 – $35,000 | See site | 24 hours | No hard credit pull for rates |
| Citi | $3,000 – $100,000 | 60 months | See site | See site |
| Alliant Credit Union | See site | See site | See site | See site |
| MedLoan Finance | $500 – $100,000 | 18 months (interest free) | See site | All credit histories |
| United Bank | See site | See site | See site | See site |
1. JetzLoan
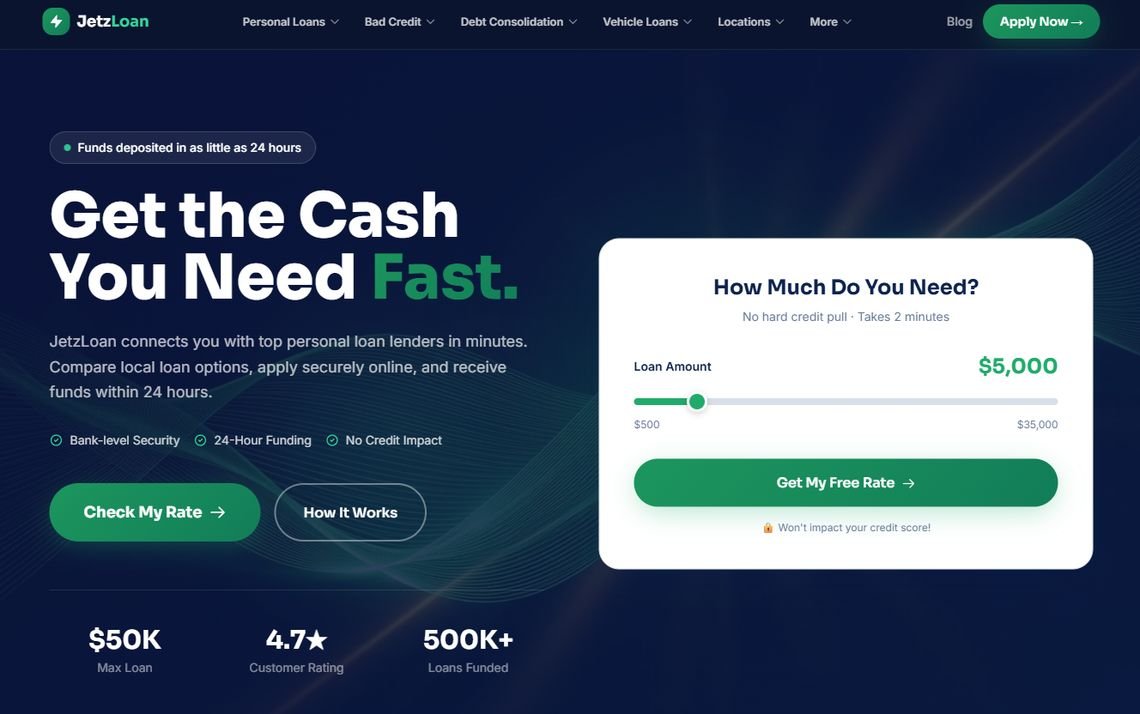
JetzLoan acts as a lightning-fast bridge for those who need cash in a hurry. It is an excellent choice for individuals who want to explore their options without the fear of a sudden dip in their credit score. The speed of this service is hard to beat when you are staring down an urgent bill, such as an unexpected car repair or a sudden home maintenance emergency.
Because they prioritize a digital-first approach, the friction of traditional banking—long wait times, physical paperwork, and manual processing—is largely removed. (jetzloan.com)
This lender is particularly well-suited for those looking at debt consolidation or vehicle loans. By consolidating high-interest credit card debt into a single, fixed-rate loan, you can simplify your monthly budget and potentially lower your overall interest rate. Because they connect you with top lenders in minutes, the process feels much more like a modern digital experience than a traditional bank meeting. It is built for the fast-paced lifestyle of 2026, where waiting days for a decision is no longer acceptable.
Pros:
- Funds can be deposited in as little as 24 hours.
- No hard credit pull to check your rates.
- High customer rating of 4.7 stars.
Cons:
- Maximum loan amount is capped at $35,000.
2. Citi
Citi is a heavy hitter in the banking world, offering a level of sophistication that comes with a global institution. They provide a wide range of products, from high-end credit cards to substantial personal loans. It is a great option for someone who wants to keep all their financial eggs in one very large basket.
For many, having a single institution handle their mortgage, personal loan, and checking account allows for better oversight of their total net worth through a unified digital dashboard. This centralized view can make managing money much simpler for busy professionals.
For those looking at mid-range financing, their personal loans offer a predictable structure. While their terms may not reach the twelve-year mark, their ability to handle larger sums up to $100,000 makes them a formidable player for significant life expenses like wedding costs or major home renovations. The stability of a major bank provides peace of mind; you aren’t worried about a small fintech startup suddenly changing its terms or going out of business. However, this stability often comes with stricter underwriting standards, meaning you generally need a solid credit history to secure their best rates.
Pros:
- High loan limits up to $100,000.
- Extensive range of financial products including investing.
- Strong digital banking infrastructure.
Cons:
- Repayment terms are limited to 60 months.
3. Alliant Credit Union
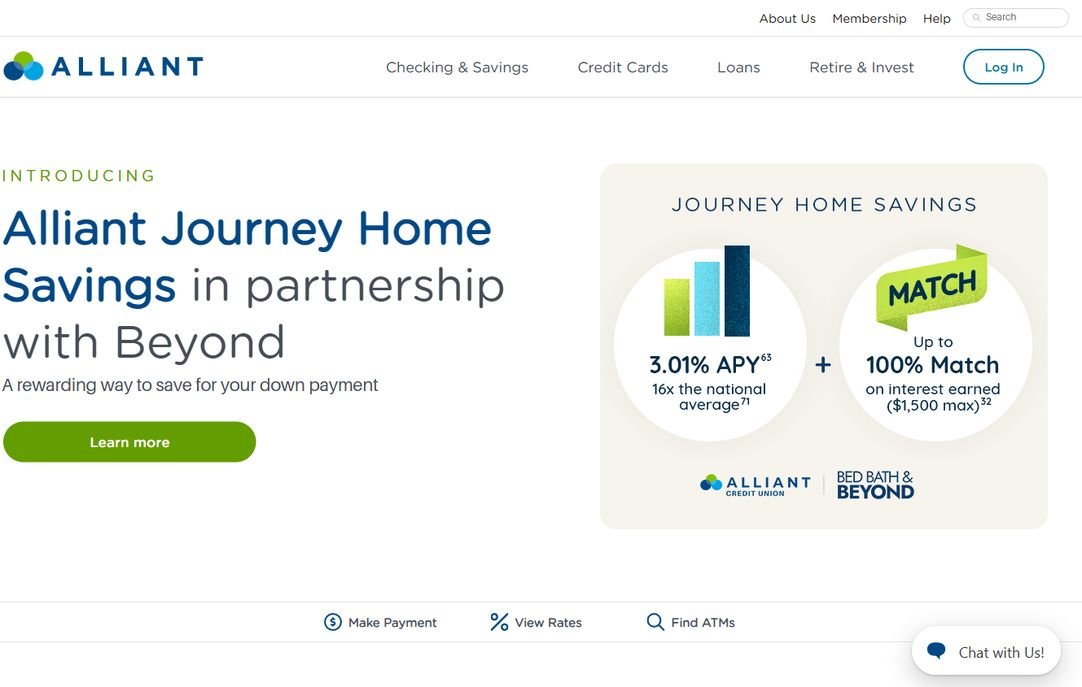
Alliant Credit Union represents the community-focused side of lending. They offer specialized savings products and high-yield accounts that make them more than just a place to borrow money. It is a holistic approach to banking that rewards members who want their money to work harder for them.
Unlike traditional commercial banks that exist primarily to maximize shareholder profits, credit unions are member-owned cooperatives. This structure often translates to more competitive interest rates and lower fees for the consumer. You get a seat at the table when things get decided.
This is a fantastic option for the disciplined saver who also needs a reliable source of credit. Their high-rate savings accounts and jumbo checking options suggest a lender that understands the importance of interest working in your favor, not just against you. If you are planning for a long-term goal—such as a down payment for a house in five years—Alliant provides the tools to grow your capital while simultaneously offering the credit lines you might need for transitional expenses. It is a balanced way to manage wealth through a cooperative model.
Pros:
- High-rate savings options significantly above national averages.
- Member-focused benefits like unlimited ATM rebates.
- Predictable growth through high-yield certificates.
Cons:
- Membership requirements often apply to credit unions.
4. MedLoan Finance
MedLoan Finance is a specialist, cutting through the noise to focus specifically on medical expenses. If you are facing a surgery or a significant dental procedure, this lender understands the specific nature of those costs. General personal loans can sometimes feel impersonal or difficult to secure when you are already dealing with the stress of health issues.
MedLoan Finance removes that layer of friction by specializing in the healthcare sector. They are remarkably inclusive, working with people from all credit histories and backgrounds. Whether you need help with a cosmetic procedure or an insurance co-payment, they aim to find a fit. This inclusivity is a key differentiator.
Where a major bank might see a medical debt as a risk, MedLoan Finance sees it as a specific, manageable expense with a predictable outcome. It is a niche service that performs well when the need is highly specific and non-negotiable, such as emergency procedures or elective surgeries that improve quality of life.
Pros:
- Specialized for medical and cosmetic procedures.
- Accepts a wide range of credit histories.
- No pre-payment penalty.
Cons:
- Very short terms for interest-free options.
5. United Bank
United Bank operates with a local touch, focusing on the personal relationship between the banker and the client. They offer a suite of products ranging from mortgages to small business loans. It is the kind of institution that feels like a neighbor rather than a faceless algorithm. In an era of automated chatbots and AI-driven loan approvals, the ability to sit down with a human being to discuss your financial goals can be invaluable, especially for complex financing needs.
For those who find the current interest rate environment intimidating, United Bank offers a guiding hand. They focus on helping customers achieve homeownership and long-term stability. This relationship-based model is particularly beneficial for entrepreneurs or small business owners who may not fit neatly into the rigid credit scoring models used by online lenders.
A local banker can look at your cash flow, your business plan, and your local reputation to approve a loan that a computer might automatically reject. It is a solid choice for someone who prefers a more traditional, relationship-based banking model. They see the person behind the paperwork.
Pros:
- Personalized guidance for complex loans like mortgages.
- FDIC-insured and backed by government security.
- Wide variety of personal and business services.
Cons:
- Likely requires more physical or direct interaction.
Understanding the Impact of Interest Rates and Inflation
When taking out a long-term loan, you must consider the macroeconomic environment. There is a significant difference between a fixed-rate loan and a variable-rate loan. A fixed-rate loan offers the peace of mind that your monthly payment will never change, providing a stable foundation for your monthly budget. However, a variable-rate loan might offer a lower starting point, which can be attractive if you believe interest rates will trend downward.
The risk is that if inflation rises and central banks raise rates, your monthly payment could climb significantly, potentially straining your budget. You are essentially gambling on the direction of the economy. It is a bet that doesn’t always pay off for the borrower.
Furthermore, inflation actually works in favor of the borrower on long-term fixed-rate debt. If you borrow $20,000 today and pay it back over twelve years, the «value» of those dollars will likely be lower in 2038 due to inflation. You are paying back the bank with «cheaper» money. This is why many investors and homeowners prefer long-term fixed debt—it acts as a hedge against inflation, provided the interest rate you secured was lower than the rate of inflation over that period.
The Hidden Costs: Fees and Fine Print
Beyond the interest rate, you must scrutinize the «extra» costs that can inflate the total cost of your loan. Common fees include:
- Origination Fees: A one-time fee charged by the lender for processing the loan, often taken directly from the principal.
- Late Payment Fees: Charges applied if you miss a deadline, which can also impact your credit score.
- Administrative Fees: Small, recurring charges for maintaining the account or providing statements.
- Late Charge vs. Default Interest: Some lenders increase your interest rate significantly if you miss a payment, moving from a standard rate to a «penalty rate.»
Before signing, request a «Truth in Lending» disclosure. This is a standardized document that clearly outlines the total amount you will have paid by the time the loan is finished. It is the most honest number in the entire lending process. Do not skip this step.
Navigating Your Loan Journey
When you are looking at a twelve-year timeline, the most dangerous mistake is ignoring the total cost of interest. A low monthly payment might look beautiful on paper today, but over a decade, that extra interest can add up to the price of a luxury car. Always ask for the total repayment amount before signing. If you are comparing two loans, compare the total cost, not just the monthly payment. A $200 monthly payment for 12 years is much more expensive than a $300 monthly payment for 5 years, even though the latter feels more «expensive» on a month-to-month basis.
Another pitfall is failing to check for pre-payment penalties. If you get a bonus or a raise in three years, you want to be able to kill that debt immediately without being punished by the bank. Some lenders make their profit from the interest you *would* have paid if you hadn’t paid the loan off early; they bake this «lost profit» into a penalty fee. Always look for lenders that allow you to pay off the balance early without a fight. This flexibility is the ultimate insurance policy for your future self.
Finally, do not rush the process just because you are in a pinch. Even with the speed of modern fintech, taking an extra day to read the fine print can save you thousands. A loan is a tool, but if used incorrectly, it can become an anchor that holds you back from your true financial potential. Approach your long-term debt with the mindset of an investor: understand the cost, understand the terms, and always have an exit strategy.
De Megaways-motor liet gokkasten los van het vaste raster met een gelijk aantal symbolen per rij. Bij elke draai krijgt elke rij een eigen hoogte, waardoor het aantal winmogelijkheden voortdurend verschuift. Dat principe is inmiddels door veel studio's overgenomen.
Cascades en het aantal winmogelijkheden
Cascades zorgen ervoor dat een enkele draai meerdere opeenvolgende winsten kan opleveren zonder dat u opnieuw inzet. Wie deze motor wil uitproberen kan Win Beast Casino en de beschikbare varianten bekijken. Het hoge aantal winmogelijkheden betekent niet dat winnen makkelijker is, want de uitbetaling per combinatie is er ook op aangepast.
| Onderdeel | Bereik | Effect |
|---|---|---|
| Symbolen per rij | 2 tot 7 | Wisselt per draai |
| Winmogelijkheden | Enkele honderden tot 117649 | Verandert steeds |
- Verwacht een hoge variantie
- Stem uw inzet af op langere droge periodes
- Controleer het uitkeringspercentage van de variant
Het wisselende speelveld maakt elke draai anders en dat is precies de aantrekkingskracht. Aan het huisvoordeel verandert de motor niets. Speel met een vast bedrag, laat u niet meeslepen door een reeks cascades en spreek van tevoren een eindtijd af.
About Post Author

