
The Best Flooring Financing Options: A 2026 Ranking of Top Lenders
The Best Flooring Financing Options: A 2026 Ranking of Top Lenders
Last updated: 2026-10-16
Renovating a home is a massive undertaking that often feels like a second mortgage. When the old linoleum starts peeling or the hardwood looks dull, the immediate urge is to fix it. However, staring at a massive invoice for new tile or laminate can be a sobering reality check for most household budgets. The cost of materials alone—from high-end engineered hardwood to premium porcelain tile—can escalate quickly when you factor in subfloor preparation, underlayment, and transitions.
Finding the right way to pay for these upgrades is just as important as choosing the right color. Whether you are looking for quick cash to cover a small repair or a long-term plan to remodel an entire house, the financing options in 2026 offer plenty of paths. The decision you make today will dictate whether your renovation remains a dream or becomes a source of financial resentment.
- FastLendGo
- HFS Financial
- Acorn Finance
- Wisetack
- Affirm
- Floor Daddy
Evaluating the Top Lenders for Home Improvements
Selecting a lender isn’t just about finding the lowest number on a screen. It requires looking at how quickly the money hits your bank account and how much stress the application process will cause. A high interest rate might seem manageable until you realize how long the term actually lasts. For example, a $10,000 loan at a 10% interest rate over 3 years costs you about $1,750 in interest. The same loan over 7 years could cost you nearly $4,000. You must weigh the immediate relief of a lower monthly payment against the long-term cost of debt.
The evaluation process focused on accessibility, speed, and the impact on credit scores. Every option was weighed against its ability to serve different types of borrowers, from those with pristine credit to those who are struggling to keep their heads above water. We looked at transparency and the ease of the digital application process, prioritizing lenders that provide clear disclosures rather than those that hide fees in the fine print.
| Lender | Loan Amounts | Credit Requirements | Key Features |
|---|---|---|---|
| FastLendGo | $500 – $5,000+ | Good to Bad Credit | Quick access to cash |
| HFS Financial | see site | No equity required | Low-fixed rates |
| Acorn Finance | see site | Good and Bad Credit | $0 dealer fees |
| Wisetack | see site | Soft credit check | Up to 24-month 0% APR |
| Affirm | see site | No credit check options | Flexible payment plans |
| Floor Daddy | see site | see site | 48 Months 0% Financing |
1. FastLendGo
FastLendGo works as a versatile bridge for those who need cash quickly for various needs, including home repairs. It is particularly useful for people who find themselves in a pinch and need to compare local personal loan options without jumping through endless hoops. This lender is ideal for the «emergency» scenario—such as a sudden leak under a new floor or a broken stair tread—where the primary goal is speed of funding rather than the absolute lowest interest rate. (fastlendgo.com)
This lender caters to a wide spectrum of financial backgrounds. Whether it is a $500 emergency for a small repair or a larger $5,000 loan for something more significant, the platform is designed to find matches for high-income individuals and those with less-than-perfect credit alike. The matching algorithm works to bridge the gap between your current credit standing and the requirements of various private lenders.
Pros:
- Covers a wide range of loan sizes from $500 up to $5,000 and beyond.
- Serves a diverse range of credit scores, from fair to bad.
- Provides a streamlined way to compare personal loan options online.
Cons:
- May not offer the most competitive rates for those with excellent credit.
2. HFS Financial
HFS Financial positions itself as a specialist for those who want to avoid the headache of traditional equity-based loans. It is a strong contender for homeowners who want to upgrade their floors without putting their property at risk as collateral. Traditional Home Equity Lines of Credit (HELOCs) can be intimidating because they use your home as security. If you default, your house is on the line. HFS Financial provides an alternative route that keeps your home’s title decoupled from the personal loan.
The main draw here is the speed of the approval process. They aim to get customers approved quickly, allowing you to move from the «dreaming» phase to the «installing» phase without waiting weeks for a bank to review your paperwork. This is particularly helpful when you have found a contractor who is ready to start immediately but you are waiting on funds to clear.
Pros:
- No equity is required to secure a loan.
- Offers low-fixed rates for stability.
- Fast approval process for quick project starts.
Cons:
- Fixed rates might be less flexible than variable options in some markets.
3. Acorn Finance
Acorn Finance is a powerhouse for those who want to avoid the «hidden costs» often associated with contractor financing. They specialize in connecting borrowers with various lenders, ensuring that the dealer fees don’t eat into the project budget. Many contractors add a «financing fee» of 10-20% to the total bill if you choose their preferred lender. Acorn works to mitigate this impact by finding direct consumer-to-lender matches.
One of the standout features is the ability to check personalized rates without a hard credit check. This is a massive relief for anyone who is worried about their credit score dropping before they even know if they can afford the work. You can use this tool to build a «budget range» before you even call a contractor for a quote, giving you more leverage during the negotiation phase.
Pros:
- Zero dealer fees for the consumer.
- Soft credit checks allow for rate checking without credit impact.
- Highly rated for customer experience.
Cons:
- The variety of lenders means rates can vary significantly between offers.
4. Wisetack
Wisetack is a favorite among service professionals because it integrates so smoothly into the existing payment workflow. It is less about the bank and more about the transaction between the customer and the contractor. For the homeowner, this means less paperwork and more directness. You don’t have to go out and find a loan; your contractor likely already offers Wisetack as a payment option.
If you are looking for a way to pay your flooring installer through a simple text or invoice link, this is it. It offers a 24-month 0% APR option which can be a lifesaver for those who want to spread out the cost without adding interest to the bill. This is particularly effective for medium-sized projects, such as replacing the flooring in a single large room or a master bathroom.
Pros:
- Extremely fast 60-second approvals.
- 0% APR options available for up to 24 months.
- High customer satisfaction ratings.
Cons:
- Terms and availability may depend on your specific contractor’s setup.
5. Affirm
Affirm has become a household name in the «Buy Now, Pay Later» movement. It is incredibly convenient for smaller flooring projects or buying materials directly from retailers that partner with the service, such as large-scale home improvement big-box stores. If you are doing a DIY renovation and just need to purchase $2,000 worth of luxury vinyl plank, Affirm is often the easiest path.
The flexibility here is unmatched. You can choose between interest-free plans for shorter periods or longer, more manageable monthly payments. It is a very transparent way to shop, as you see exactly what you will pay upfront. There are no «gotcha» moments where your interest rate suddenly changes mid-payment; the terms are locked in at the point of sale.
Pros:
- No hidden fees and high transparency on interest.
- Flexible plans including interest-free options for certain purchases.
- Extremely easy to use via an app or online.
Cons:
- Not all flooring contractors are equipped to use Affirm.
6. Floor Daddy
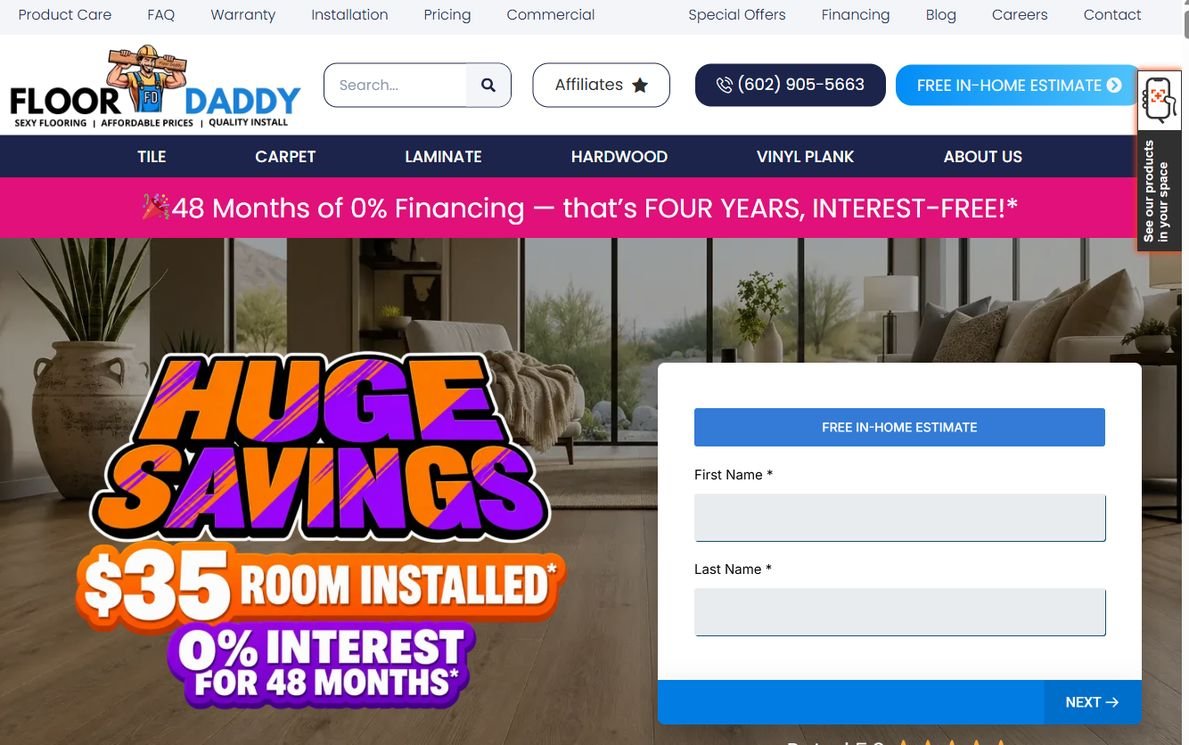
Floor Daddy is a specialized local option that focuses on the actual installation as much as the financing. This is ideal for someone who wants a «one-stop shop» where the payment plan and the labor are tied together. This eliminates the risk of having the materials delivered but having no funds left over to pay the professional to lay them.
They offer a significant 48-month 0% financing option, which is quite rare. This allows you to spread the cost over four full years without the weight of interest, making large-scale renovations much more palatable for the average family. For a $10,000 project, paying $208 a month for four years is a much easier pill to swallow than a single $10,000 lump sum or a high-interest credit card payment.
Pros:
- Long-term 0% financing for up to 48 months.
- Includes professional floor prep and dustless removal options.
- Highly rated with a 5.0 star reputation.
Cons:
- Financing is likely tied specifically to their own installation services.
Financing Strategies: Comparing Loan Types
Before you commit, it is essential to understand the structural differences between the financing methods you are considering. Choosing the wrong type of loan can result in unexpected tax implications or long-term debt cycles. Use the following comparison to determine which direction fits your specific project scale.
| Financing Type | Best For… | Key Risk | Speed of Funds |
|---|---|---|---|
| Personal Loan | Total control of cash for DIY or various contractors | Higher interest rates for lower credit | 1–3 Business Days |
| 0% APR Financing | Mid-sized projects with high-end materials | Must pay in full before promo period ends | Instant (at checkout) |
| Home Equity Loan | Major, whole-home renovations | Property is collateral for the debt | Weeks to Months |
| Buy Now, Pay Later | Material purchases and small repairs | Easy to overspend on small items | Immediate |
When evaluating these, consider your «exit strategy.» If you plan to sell your home in two years, taking out a long-term home equity loan is a mistake, as it adds a lien to the title that must be cleared during the sale. If you are staying in the home for the next decade, a fixed-rate personal loan provides a predictable, stable way to enhance your property value without the volatility of a variable interest rate.
Navigating the Financing Maze
Before signing anything, it is vital to look at the total cost of the loan, not just the monthly payment. A low monthly payment that lasts for five years can end up costing you significantly more than a higher payment over twelve months. Always ask for the total amount payable over the life of the loan. This «Total Cost of Borrowing» figure is the only number that truly matters when comparing two different lenders.
Another common mistake is assuming all «no credit check» options are free. While some lenders allow you to check your rates without a hard inquiry, the actual loan will almost always involve a credit check. Always use the soft-pull options first to protect your score while you shop around for the best deal. A single hard inquiry might drop your score by 5 points, but multiple inquiries in a short window can signal «credit hunger» to lenders and trigger much higher interest rates.
Lastly, ensure your project scope is finalized before you commit to a specific loan amount. It is much easier to borrow more money at the start than it is to try and add more to a loan once the installer has already started laying the tile. Contractors often discover unexpected issues—like subfloor rot or uneven joists—once they tear up the old flooring. Always include a 15-20% «contingency buffer» in your loan request to cover these inevitable surprises. Plan for the unexpected, and you will avoid a financial headache.
Few casino formats are as transparent as video poker. The pay table is printed on the screen, the maths is fully knowable, and correct play is a matter of following a chart rather than guessing.
Pay Tables Decide Video Poker Returns
The classic nine six Jacks or Better pay table returns above ninety nine percent with optimal play, while reduced versions drop noticeably for the same game name. Players checking which pay tables an operator offers can Online Godz Casino and compare variants side by side. Strategy charts exist for every major version and are straightforward to learn.
| Variant | Optimal Return |
|---|---|
| Jacks or Better 9/6 | 99.5% |
| Deuces Wild | 98.9% |
| Jacks or Better 8/5 | 97.3% |
- Look up the full house and flush payouts first
- Learn one variant properly rather than several loosely
Because every decision has a demonstrably correct answer, video poker suits players who enjoy getting things right. The edge remains small but real even with perfect play. Stick to one variant, follow its chart, and think of the low margin as longer playing time rather than profit.
About Post Author

