
The 7 Best Lenders for Bad Credit Loans in New Jersey for 2026
The 7 Best Lenders for Bad Credit Loans in New Jersey for 2026
Last updated: 2026-10-16
When a sudden car repair or a medical bill hits, hitting a financial brick wall feels all too real. Many New Jersey residents find themselves in this exact spot, staring at a mounting debt they didn’t see coming. You need a lender that looks past a single credit score to see if you actually have the means to pay them back.
Whether you are stuck with a broken transmission in Newark or facing a surprise dental bill in Jersey City, the stress of a crisis often makes it hard to do your homework. You might feel rushed to sign anything just to solve the immediate problem, but that impulse can lead to much bigger headaches down the road.
Sorting through the sea of lenders requires a sharp eye and a realistic mindset. Some companies offer cash in a heartbeat but charge a premium for the speed, while traditional banks offer more stability but move much slower. This list focuses on finding a middle ground for those with poor credit who want to stay financially healthy.
There is a massive difference between a high-interest installment loan and a structured medical payment plan. Choosing the wrong one can turn a temporary setback into a lifelong cycle of debt. Use this guide to weigh your options carefully before you sign any paperwork.
- Max Cash
- FastLendGo
- XCEL Federal Credit Union
- Fulton Bank
- Loanz
- Cherry
- CareCredit
Evaluating Financial Options Across New Jersey
Deciding which lender actually works for your specific situation requires looking at several different metrics. Most people in an emergency care about speed above all else. If your car is your only way to get to work in a commuter state like New Jersey, waiting three days for a loan might be impossible.
However, the total cost of the money you borrow is what keeps you afloat in the long run. You have to account for interest rates and those sneaky hidden fees. A quick loan is useless if the interest rates swallow your entire paycheck every month.
We also looked at how much flexibility these lenders offer when your credit history isn’t perfect. Some provide title loans if you have no collateral, while others specialize in medical financing. This covers everything from a tiny $250 cash advance to a massive $60,000 signature loan.
We focused on whether a lender cares more about your income or your credit score. Generally, your ability to pay—your actual income and employment—is a much better predictor of whether you will stay on track than a single number on a credit report.
| Lender Name | Loan Amounts | Funding Speed | Credit Requirements |
|---|---|---|---|
| Max Cash | $250 – $10,000+ | Minutes | Bad Credit Options |
| FastLendGo | Small Loans Available | Quick Access | Bad Credit/No Credit |
| XCEL Federal Credit Union | $500 – $60,000 | See Site | Secured/Unsecured |
| Fulton Bank | See Site | See Site | See Site |
| Loanz | $100 – $10,000 | Quick/Convenient | See Site |
| Cherry | See Site | Instant Approval | High Approval Rate |
| CareCredit | See Site | Instant Decisions | Subject to Credit |
1. Max Cash
Max Cash acts like a one-stop shop for various financial needs. Their products range from small $250 advances to larger loans that go over $10,000. This makes them a solid choice if you need immediate relief from an unexpected expense. A $500 loan might fix a broken appliance, while the larger options help with car or home repairs.
The platform is built for speed. They target people who need installment or title loans in just a few minutes. Because they work with people who have bad credit, they offer a lifeline that big-box banks often won’t. Just keep in mind that being fast often means you will pay a higher interest rate.
Pros:
- Extremely fast processing for urgent needs.
- Wide variety of loan types including title loans.
- Accessible for those with bad credit.
Cons:
- Title loans require collateral, risking your vehicle.
2. FastLendGo
FastLendGo is a flexible option for personal financing. They work with all kinds of credit tiers, whether you have good, fair, or bad credit. It is a simple way to compare local options without driving from branch to branch. (fastlendgo.com)
This lender is great for specific life events like dental work or fixing your car. If you are searching for personal loans nearby, their online model simplifies that hunt. They aggregate different profiles to help match your credit score with a provider that actually wants your application.
Pros:
- Covers various life expenses like roof and dental repairs.
- Options for those with no credit history.
- Easy online comparison tool.
Cons:
- Focus is primarily on online comparisons rather than direct banking.
3. XCEL Federal Credit Union
If you want more traditional stability, XCEL Federal Credit Union offers secured and signature loans. Their loan amounts can reach up to $60,000, which provides a significant cushion for big life changes. You could use these funds for debt consolidation, home upgrades, or unexpected medical bills.
As a credit union, they feel a bit more community-focused than predatory lenders. Credit unions are owned by members rather than shareholders, which often leads to more personalized service. You can choose between secured and unsecured loans to find what fits your situation. Using a savings account as collateral can often unlock much lower rates.
Pros:
- High maximum loan amounts up to $60,000.
- Offers secured loan options for better rates.
- Member-focused service model.
Cons:
- Likely requires membership or specific eligibility.
4. Fulton Bank
Fulton Bank is a major name for New Jersey residents. They have the strength of a large institution but still maintain a local feel. This makes them a solid choice for long-term banking and managing more complex financial needs over several years.
They offer everything from personal to commercial banking. They might not be the fastest choice for a $200 emergency, but they are excellent for managing significant wealth or business investments. Their stability is a big plus if you want a lender that will still be around decades from now.
Pros:
- Highly secure and FDIC-insured.
- Wide range of banking services from personal to commercial.
- Strong presence in the New Jersey market.
Cons:
- May have stricter requirements than specialized bad credit lenders.
5. Loanz
Loanz focuses on helping you manage your future through specific loan solutions. With amounts between $100 and $10,000, they are great for smaller debt consolidation or upcoming costs like moving or weddings. This allows you to handle small problems before they turn into massive debts.
The main goal here is getting your life back under control. Their debt consolidation products help you manage multiple bills at once. Instead of tracking five different due dates, you can combine them into one monthly payment to simplify your budget and lower your interest stress.
Pros:
- Low entry point for small loans starting at $100.
- Specific products for debt consolidation.
- Convenient digital transactions.
Cons:
- Loan amounts are capped at a relatively modest $10,000.
6. Cherry
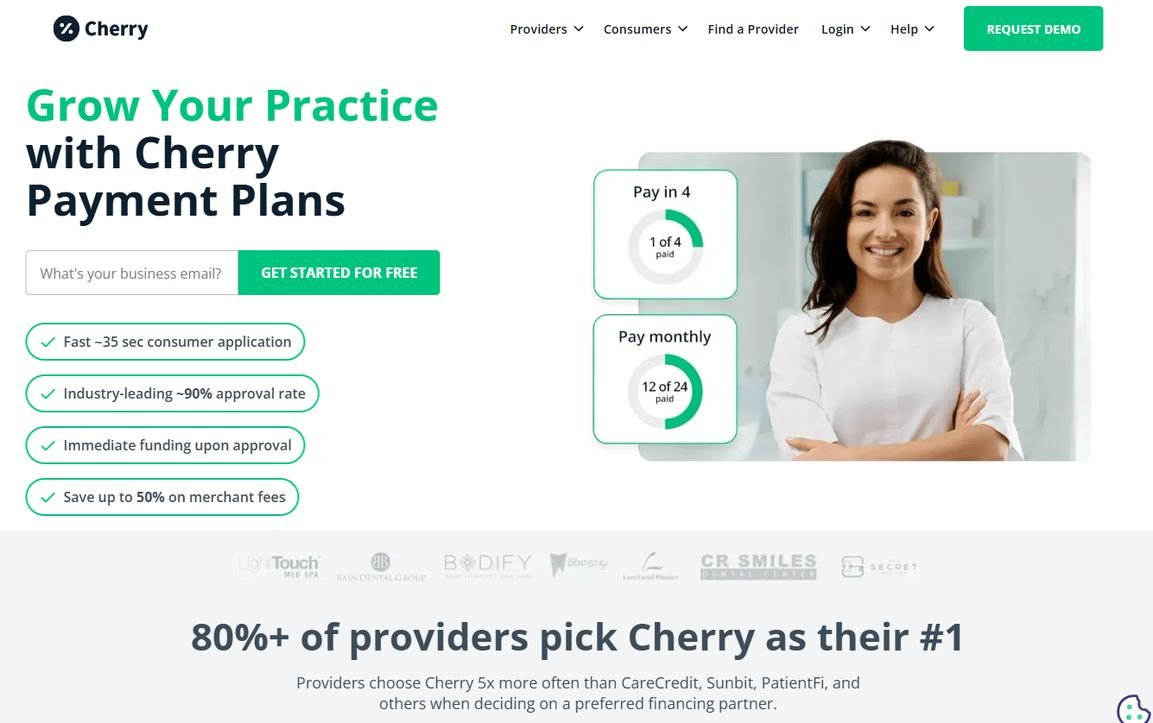
Cherry is a specialist in the healthcare and retail finance world. They have an impressive 90% approval rate and are used by thousands of providers. Their main goal is to let you get necessary services now and pay for them later, removing the immediate cost barrier.
The application process is incredibly fast, often taking only 35 seconds. This is a top choice for people who need dental work or home repairs immediately but want to spread out the costs. Cherry works directly through your service provider to make the process easy.
Pros:
- Extremely fast application process.
- High approval rate for consumers.
- Direct integration with many healthcare providers.
Cons:
- Limited to specific merchants and providers.
7. CareCredit
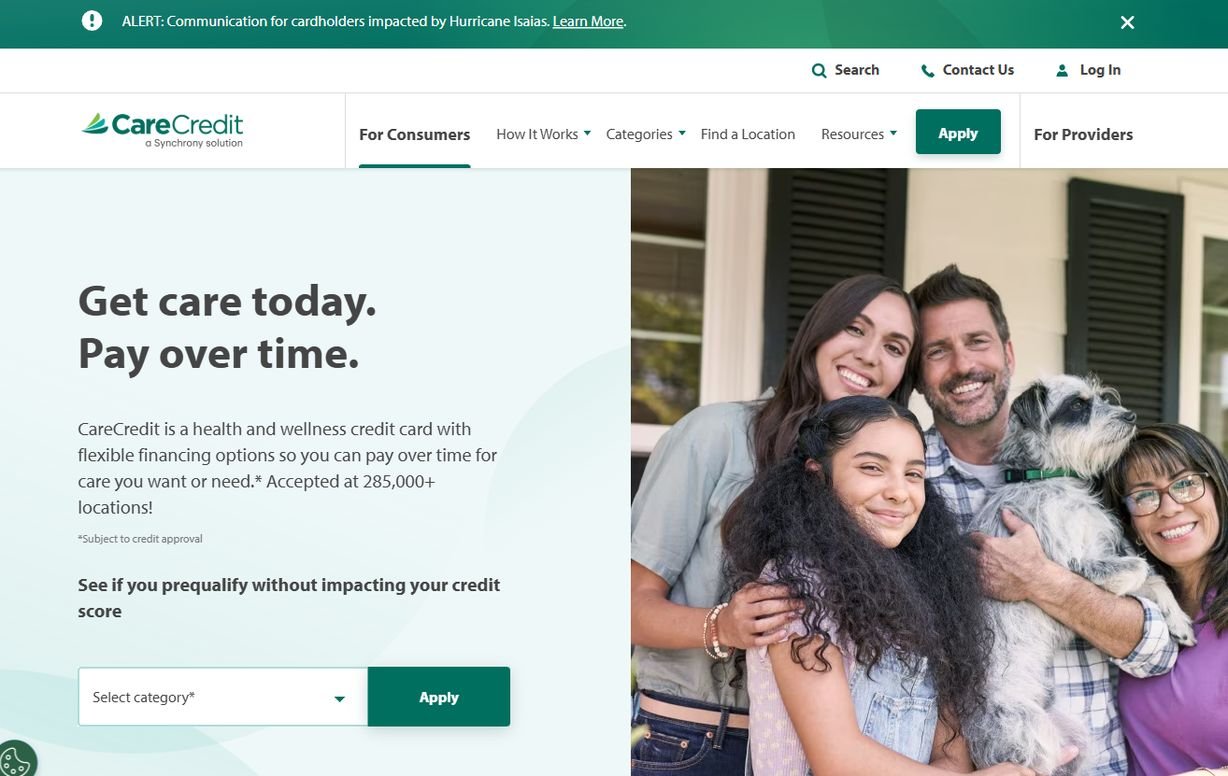
CareCredit is a credit card built specifically for health and wellness. It is accepted at over 285,000 locations, which makes it one of the most versatile tools for medical costs. You can use it for vision, dental, or even veterinary expenses.
You can check if you prequalify without hurting your credit score. This is vital if you are worried about your standing while you shop for medical options. Many plans offer «no interest if paid in full» deals, but be careful—missing a deadline can result in retroactive interest charges.
Pros:
- No impact on credit score during prequalification.
- Massive network of accepted locations.
- Flexible financing for health and wellness.
Cons:
- Subject to credit approval and specific terms.
Understanding the Differences Between Secured and Unsecured Loans
Before you apply for anything, you need to know if a loan is secured or unsecured. This choice changes your risk level completely. A secured loan is backed by an asset, like your car, your home, or a savings account. Because the lender can take that asset if you stop paying, they are usually more willing to work with lower credit scores.
Secured loans often come with lower interest rates, but the risk to you is much higher. If you miss payments on a title loan, you could lose your vehicle. It is a trade-off between a lower rate and the risk of losing your property.
An unsecured loan isn’t backed by any physical asset. Most personal loans and credit cards fall into this category. Since the lender can’t immediately take your car if you default, they charge higher interest rates and demand better credit scores. If you fail to pay, they can’t take your house instantly, but they can sue you or garnish your wages.
How to Prepare for a Loan Application
You can increase your chances of getting approved and getting a better rate by having a plan. Following these steps helps you avoid unnecessary hits to your credit score:
- Verify Your Documentation: Gather your recent pay stubs, bank statements, and ID before you start. If you are using an asset as collateral, have proof that you actually own it.
- Audit Your Debt-to-Income (DTI) Ratio: Lenders look at how much of your income goes to existing debt. If that number is too high, you might get denied. Try paying down small balances before you apply.
- Check for Errors in Your Credit Report: One wrong late payment can ruin your score. Use a free service to find and dispute mistakes before you go looking for money.
- Compare APRs, Not Just Interest Rates: The Annual Percentage Rate (APR) includes interest and mandatory fees. This is the real cost. A 10% rate with a $500 fee might be more expensive than a 12% rate with no fees.
- Use Prequalification Tools: Look for lenders that offer «soft pulls.» This lets you see your estimated rates without leaving a permanent mark on your credit report.
Avoiding Common Financial Pitfalls
Choosing a lender isn’t just about finding the first person to give you cash. You have to read the fine print. Many people take a high-interest loan just because they are in a rush. This can trap you in a cycle where the total interest you pay is actually higher than the money you originally borrowed.
Always look at the total cost of the loan, not just the monthly payment. A small monthly payment might hide a very long term that costs you thousands more in interest. A $5,000 loan with a $100 payment sounds great until you realize you’ll be paying it for seven years.
One mistake to avoid is applying for too many loans at once. Every application can trigger a «hard inquiry,» which lowers your score. If you apply for five loans in one week, banks will think you are desperate for cash. Use prequalification tools first to narrow your list before you make any official moves.
Cashback returns a percentage of net losses over a defined period, usually weekly. Unlike match bonuses it arrives after play rather than before, which makes it easier to value accurately but also means it only ever triggers on a losing run.
Cashback Compared With Match Bonuses
The critical question is whether cashback pays as withdrawable cash or as bonus credit carrying further wagering. Players comparing rebate structures across operators can Richard Online Casino and check payout terms before choosing where to concentrate play. Percentages typically sit between five and fifteen percent, often scaling upward with loyalty tier.
| Term | Why It Matters |
|---|---|
| Payment form | Cash beats bonus credit |
| Calculation period | Weekly and monthly differ |
- Compare the effective rate after wagering is applied
- Do not treat a rebate as a reason to play on
Cashback softens losing sessions without ever making them profitable, and it is worth remembering that receiving it means the week went badly. Genuine cash rebates have clear value. Bonus credit with attached wagering mostly encourages another session, which is precisely why operators structure it that way.
About Post Author

