
Top 7 Lenders for Uber Drivers Seeking Loans with Bad Credit in 2026
Top 7 Lenders for Uber Drivers Seeking Loans with Bad Credit in 2026
Last updated: 2026-10-16
Trying to manage money as a rideshare driver can feel like driving through a thick fog without any headlights. When an unexpected car repair or a medical bill pops up, the traditional banking system often turns its back on anyone with a less-than-perfect credit score. This struggle is the daily reality for many independent contractors on the road.
Unlike salaried employees who live for the predictability of a bi-weekly direct deposit, gig workers deal with constant volatility. You have to manage surge pricing, seasonal shifts in demand, and sudden maintenance costs that can wipe out a week’s earnings in a single afternoon. It is a constant balancing act of keeping the car running and the bank account full.
Finding reliable capital means looking past standard credit scores and focusing on actual earning potential. Traditional lenders often use FICO scores as the only way to judge trustworthiness. They ignore the fact that a driver might have high cash flow but a low score due to historical factors that have nothing to do with their current ability to pay their bills.
This list highlights the most effective options for drivers who need quick access to funds without the usual red tape. Your choice depends on the situation. You might need a small cushion for gas and groceries, or perhaps a larger loan to replace a transmission or invest in a more fuel-efficient vehicle.
- Ualett
- Earnin
- JetzLoan
- Dave
- BeneMoney
- Fence Outlet
- Max Cash
Evaluating Gig Economy Lending Options
The selection process for this ranking focused on speed and accessibility for people with variable incomes. Since Uber drivers do not have a traditional bi-weekly paycheck, we prioritized lenders that look at recent earnings rather than long-term credit history. In the rideshare world, liquidity is just as important as total income.
A driver who earns $1,500 a week but cannot access it until Friday is effectively broke for the first four days of the week. This gap can lead to high-interest predatory lending if you aren’t careful. Flexibility is the name of the game when you are working in the gig economy.
We looked for providers that offer rapid funding because a broken axle cannot wait for a three-day bank transfer. The comparison also checks how much each service provides and whether the application process triggers a hard credit inquiry. A hard inquiry can drop a score by several points, which might disqualify a driver from better interest rates later on.
Speed, transparency, and ease of use were the primary yardsticks we used to vet these services. We wanted to see which providers actually help drivers get back on the road without adding more stress to their lives.
| Lender Name | Max Loan/Advance | Funding Speed | Credit Impact |
|---|---|---|---|
| Ualett | See site | Fast funding | See site |
| Earnin | See site | Up to 2 days early | See site |
| JetzLoan | $50,000 | As little as 24 hours | No hard pull |
| Dave | $500 | 5 minutes or less | No credit check |
| BeneMoney | See site | Fast access | No credit check |
| Fence Outlet | See site | See site | |
| Max Cash | $10,000+ | In minutes | See site |
1. Ualett
Ualett positions itself as a financial partner designed for the ebb and flow of independent work. Instead of forcing drivers into a rigid, traditional banking box, it offers cash advances built around variable income. This makes it a strong contender for those whose weekly earnings fluctuate wildly.
If you have a high-earning weekend during a holiday surge but realize you need that money now to cover a sudden tire replacement, Ualett’s model recognizes that your income is already there, even if the platform hasn’t settled it yet. The platform focuses on providing simple solutions through a single app.
It is built for real life, aiming to help workers manage the ups and downs of the gig economy. This is ideal for drivers who need to bridge the gap between a heavy work week and a slow one. Rather than applying for a loan that requires months of documentation, Ualett looks at the data inherent in your work history to see your ability to repay.
Pros:- Designed for variable income patterns
- Flexible cash advances
- User-friendly mobile application
- Limited to specific gig worker profiles
2. Earnin
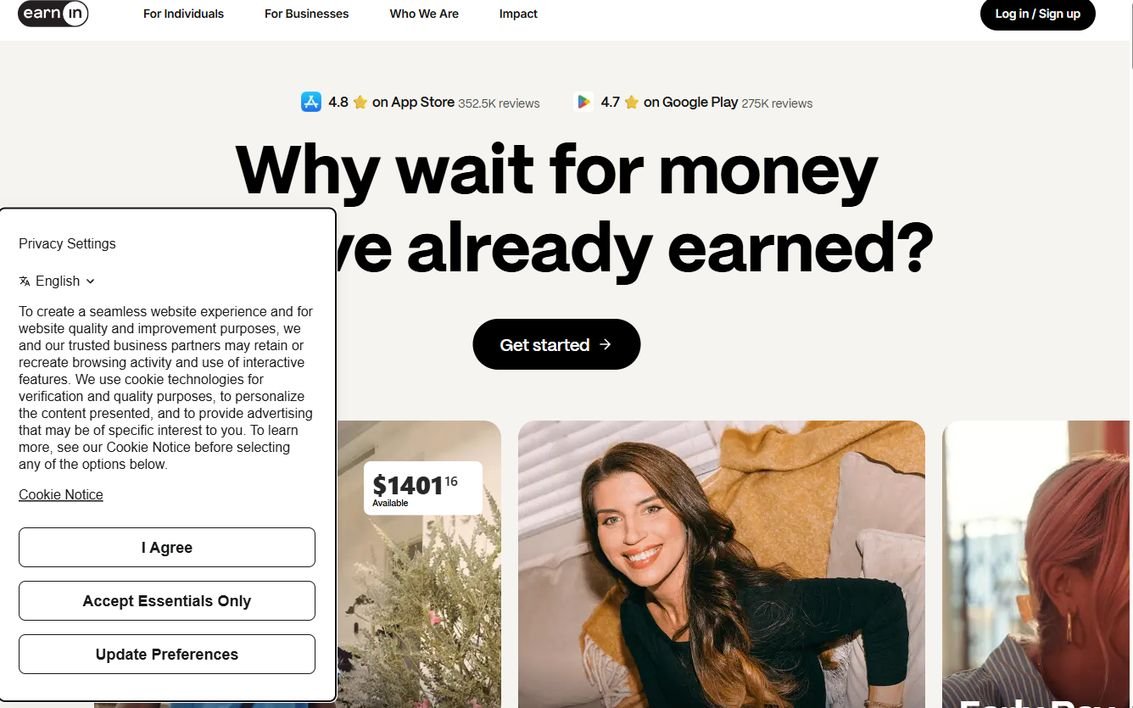
Earnin operates on a simple philosophy: why wait for money you have already earned? This service allows individuals to access their pay in real time through Live Pay. It is a lifeline for those who want to avoid the cycle of waiting for a weekly settlement to cover immediate needs.
If you’ve driven 40 hours this week and have accrued $600 in earnings, Earnin allows you to access a portion of that cash immediately. You don’t have to wait for the end-of-week payout from your rideshare app just to pay for something today.
Beyond simple cash access, the platform offers various financial health tools. Users can track credit scores, use savings jars to set aside small amounts for emergencies, and even access free career tools. It is a comprehensive ecosystem for anyone trying to move from surviving to thriving. By providing tools to save alongside tools to borrow, Earnin helps break the paycheck-to-paycheck cycle.
Pros:- Real-time pay access with Live Pay
- Includes credit monitoring and savings tools
- High user ratings on app stores
- Requires consistent work history to qualify
3. JetzLoan
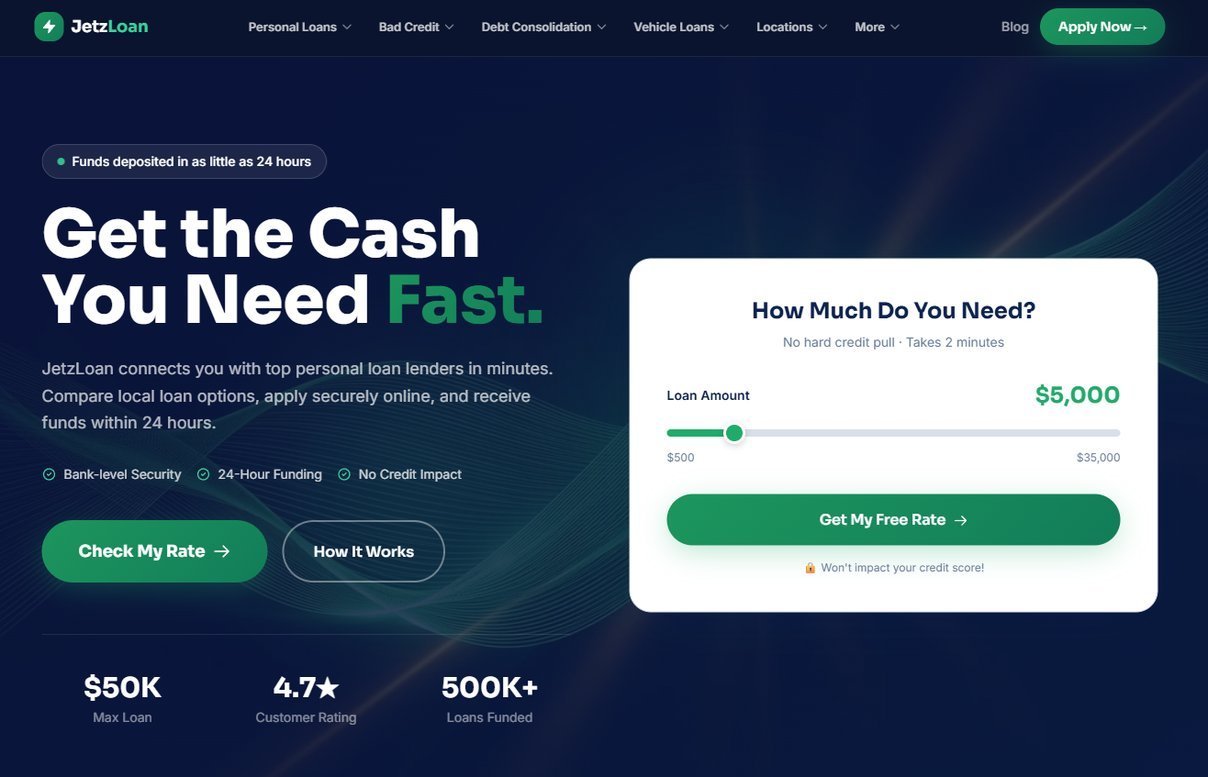
When a driver needs a significant amount of capital, JetzLoan steps up to the plate. They connect users with top personal loan lenders in just a few minutes. It is a high-speed bridge for those needing everything from small amounts to much larger sums for vehicle investments.
If your car requires a major overhaul—such as a new transmission or an entire engine replacement—a $500 advance from an app won’t suffice. You need a substantial loan that can cover parts and labor. The service is notable for its speed, with funds often deposited in as little as 24 hours.
Because they offer a «no hard credit pull» option for initial rates, drivers can shop around without fear of damaging their already fragile credit scores. This is a critical feature for those working to rebuild their credit. You can see what rates you might qualify for without any penalty, allowing you to compare offers before committing to a formal application.
Pros:- No hard credit pull for rate checks
- Fast 24-hour funding capability
- High maximum loan limits up to $50,000
- May involve higher interest rates for bad credit
4. Dave
Dave is a popular choice for those who need a quick infusion of cash to cover the basics. With the ExtraCash feature, users can access up to $500 in five minutes or less. It is designed for those «in-between» moments, such as needing gas to complete a ride or groceries for the week.
If you find yourself $40 short at the pump and it’s preventing you from earning more, Dave provides a rapid response that traditional banks simply cannot match. The technology behind the app, CashAI, analyzes various data points including bank balance and irregular work patterns.
This means the app looks at your actual financial behavior rather than just a stale credit report. If you have been driving consistently and your bank account shows regular deposits from rideshare platforms, CashAI identifies that stability even if your credit score doesn’t reflect it. It is a modern solution for the modern, non-traditional worker.
Pros:- Extremely fast approval process
- No interest or late fees for ExtraCash
- No credit checks required
- Low maximum limit of $500
5. BeneMoney
BeneMoney operates a bit differently by acting as a financial safety net through an employer-sponsored model. It is not something a driver seeks out independently, but rather something provided as a benefit. This makes it a very stable and low-stress way to handle life’s surprises.
For drivers working through larger fleet management companies or delivery services that offer benefits packages, BeneMoney can be a vital resource. The service aims to reduce the massive stress that financial instability causes during the workday. When a driver isn’t worried about an unexpected medical co-pay, they can focus more effectively on the road.
By offering no-credit-check loans and free credit counseling, it helps build a more stable workforce. If your employer offers this, it is arguably the most secure way to manage short-term cash needs because it is integrated into your professional ecosystem.
Pros:- No credit checks required
- Includes free credit counseling
- Reduces workplace financial stress
- Only available through participating employers
6. Fence Outlet
While not a traditional lender for personal cash, Fence Outlet provides specific financing for home improvement materials. For drivers who might be working on a home-based business or simply want to upgrade their property, they offer specialized packages for DIY fencing projects.
This is particularly relevant for those who use their property as a secondary source of income, such as renting out space or running a small side business from their yard. They provide everything from wood to vinyl in convenient boxes designed for self-installation.
For those looking to invest in their property value through easy-to-use materials, this is a very specific but useful resource. Instead of taking out a general-purpose loan that might carry higher interest, using a specialized provider like Fence Outlet allows you to fund a specific home improvement project with tailored solutions.
Pros:- Specialized DIY fencing packages
- Available in various materials
- Local service availability
- Not a source of general liquid cash
7. Max Cash
Max Cash acts as a one-stop shop for a wide array of financial products. They offer everything from small cash advances to larger installment loans and even title loans. This variety makes them a versatile option for drivers with very different financial emergencies.
If you need a quick $200 for a registration fee, they have you covered; if you need $5,000 for a new set of tires and brakes, they can assist with that too. The platform is built for speed, promising relief in minutes. Whether you need a small $250 boost or a larger amount to cover a major car repair, they provide a personalized inquiry process.
This allows you to see the specific terms, interest rates, and repayment schedules that apply to your unique situation. It is a high-utility option for those who need specific types of credit and want to see multiple options in one place.
Pros:- Wide range of loan amounts
- Multiple product types available
- Quick personalized inquiries
- Title loans carry significant risks
The Risks of High-Interest Debt in the Gig Economy
While many of the options listed above are designed to be helpful, it is essential to understand the difference between «liquidity» and «debt.» For a rideshare driver, there is a fine line between using a cash advance to stay on the road and falling into a debt trap. Because gig income is non-guaranteed, a high-interest loan can quickly become unmanageable if you have a week of low demand.
When evaluating any loan, calculate your «break-even» point. If you borrow $500 to fix a tire, how many additional hours of driving will it take to pay back that $500 plus interest? If the answer is 20 hours of driving, it is likely a sound investment in your tool of the trade. However, if you are borrowing $500 for a non-essential purchase and it takes 20 hours of driving to repay it, you are essentially working for the lender.
Always ensure the loan is being used to generate more income or to prevent a greater loss. Don’t let your vehicle’s maintenance costs turn into a permanent debt cycle.
Building Long-Term Financial Resilience
The ultimate goal should not just be accessing quick cash, but moving toward a state where quick cash isn’t a necessity. Drivers can build resilience by implementing small, automated financial habits. Even saving just $5 per day through an app like Earnin can create a $150 monthly buffer.
While $150 may not cover a transmission replacement, it can cover a new set of windshield wipers or a sudden increase in fuel costs. Additionally, consider the «Sinking Fund» method for vehicle maintenance. Instead of viewing car repairs as a surprise, treat them as a monthly bill.
Calculate your average monthly maintenance cost (oil changes, tires, brakes) and set that amount aside in a separate account every single month. This transforms a «crisis» into a «planned expense,» allowing you to navigate the road with much more confidence and less financial fog.
Avoiding Financial Pitfalls
When you are staring at a mounting pile of bills, the temptation to grab the first cash offer is overwhelming. However, it is vital to understand the terms of any agreement. Always check if there are hidden fees or high interest rates that could trap you in a cycle of debt.
For example, some lenders may charge «origination fees» that are taken out of your loan before you even receive it. This means you get less than you asked for but still owe the full amount plus interest. Avoid the trap of taking out multiple high-interest loans at once. While a cash advance might solve a problem today, it can create a massive headache next month.
Always aim for the simplest solution that matches the size of your problem, and prioritize lenders that do not perform hard credit pulls. By being intentional with how you borrow, you can use these tools to fuel your career rather than let them become an anchor on your earnings.
Le blackjack reste le jeu de table ou les decisions du joueur pesent le plus. La strategie de base, calculee par ordinateur il y a des decennies, indique le meilleur choix pour chaque main face a chaque carte visible du croupier. Elle ne garantit rien sur une session, mais elle reduit l'avantage de la maison.
La strategie de base et l'avantage de la maison
Une table qui paie le blackjack trois pour deux et une autre qui le paie six pour cinq n'ont pas du tout le meme cout, et l'ecart depasse largement les erreurs de debutant. Pour reperer les variantes proposees par chaque operateur, on peut Rivo Casino avant de s'asseoir. Les regles figurent dans le menu d'information de la table, il suffit de les lire.
| Variante | Paiement blackjack | Avantage maison |
|---|---|---|
| Classique | 3 pour 2 | 0,5% |
| Reduite | 6 pour 5 | 1,9% |
- Lisez les regles de la table avant la premiere main
- Les tables qui paient six pour cinq coutent nettement plus cher
Le blackjack recompense la constance, ce qui le rend interessant sans le rendre gagnant. Sur une soiree, la variance domine largement la technique. Fixez une somme que vous acceptez de perdre, suivez la grille sans l'ajuster apres une mauvaise serie, et arretez a l'heure prevue.
About Post Author

