
The Top 7 Lawn Mower Financing Options for 2026
The Top 7 Lawn Mower Financing Options for 2026
Last updated: 2026-10-16
Buying a new mower can feel like a mountain to climb. When a professional-grade zero-turn machine hits several thousand dollars, most people don’t just walk into a dealership and hand over a thick envelope of cash. They need a way to spread that cost over several months or even years.
Whether you are replacing an aging push mower with a high-end riding tractor or expanding a commercial landscaping fleet, the method of payment matters as much as the machine itself. You aren’t just buying iron and blades; you are managing a significant capital outlay.
Finding the right lender involves more than just looking at a monthly payment. You have to weigh interest rates against how a credit check might impact your score. You also need to consider how quickly the machine actually lands in your garage.
A high-interest loan might seem manageable today. However, when stretched over a 60-month term, the total cost of ownership can skyrocket. This list evaluates the most reliable paths to ownership, from manufacturer-direct deals to fast digital loans.
- Cub Cadet
- JetzLoan
- Gravely
- K and G Mowers
- Manhattan Bank
- Minute Loan Center
- Yanmar
How These Financing Providers Were Evaluated
The selection process focused on accessibility and the specific needs of different types of buyers. For a homeowner looking to upgrade their yard work, a low-interest manufacturer deal is often the golden ticket. These deals sometimes include promotional periods that allow you to pay off the equipment with zero interest, provided you stay current on all payments.
Commercial landscapers have different problems. If a machine breaks down in the middle of a busy season, they need cash by tomorrow morning, not next week. For them, a three-day approval process is essentially a three-day loss of revenue. They can’t afford to wait on a slow-moving bank while their crew sits idle.
We scrutinized each entry based on funding speed, credit requirement flexibility, and term transparency. We looked at whether a lender requires a hard credit pull and how much leeway they offer for those with less-than-perfect scores. This ensures a balanced view for everyone from the casual gardener to the fleet owner.
We also considered the «total cost of credit.» This includes not just the interest rate, but also potential origination fees, documentation costs, and prepayment penalties. You don’t want to be stuck in a loan that prevents you from paying it off early when you have extra cash.
| Lender Name | Max Loan Amount | Funding Speed | Credit Requirements | Key Feature |
|---|---|---|---|---|
| Cub Cadet | see site | see site | see site | Manufacturer Financing |
| JetzLoan | $35,000 | 24 Hours | No Hard Credit Pull | Fast Digital Funding |
| Gravely | see site | see site | Subject to Credit | Fleet Pricing Available |
| K and G Mowers | see site | see site | No Credit Impact Prequal | 0% APR for 48 Months |
| Manhattan Bank | see site | see site | see site | FDIC-Insured |
| Minute Loan Center | see site | Same Day | Fair Credit Accepted | Instant Online Approval |
| Yanmar | see site | see site | see site | Global Brand Support |
Ranking of Top Mower Financing Options
1. Cub Cadet
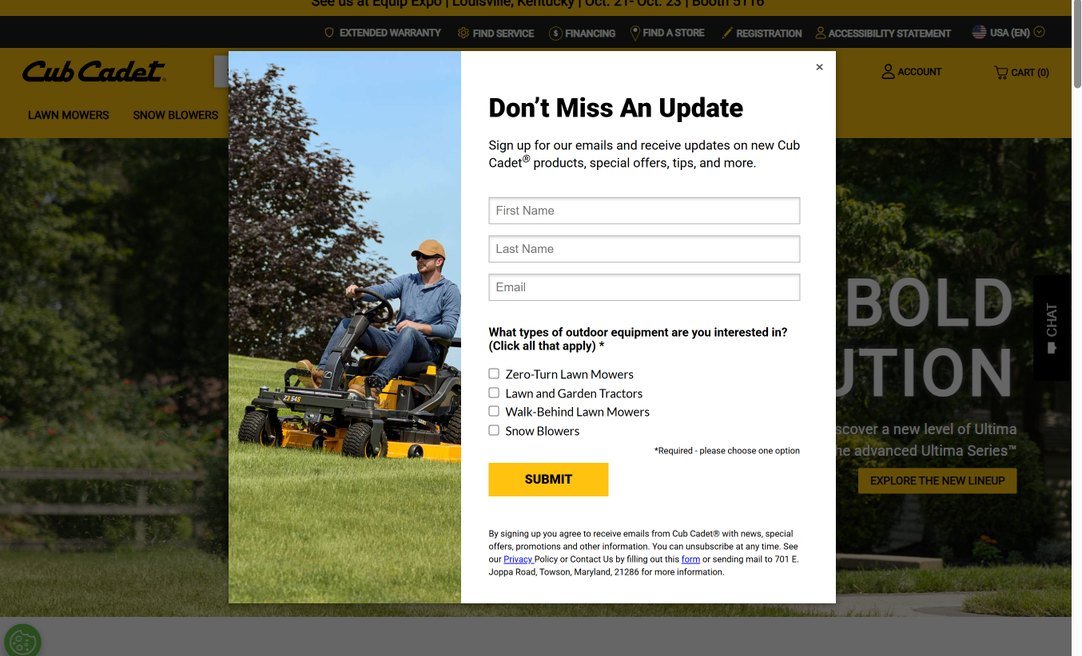
Cub Cadet offers a direct route to high-end equipment like the Ultima Series zero-turn mowers. Their financing aims to get you from the showroom floor to your first pass in record time. It is a straightforward way to acquire premium machinery without a massive upfront hit to your savings.
Because they are the manufacturer, the financing is often integrated directly into the point of sale. You don’t have to deal with a third-party bank that doesn’t understand the specific value of the equipment you are buying. It keeps things simple and localized to the brand.
This option works well for the homeowner who knows exactly which model they want and wants to stay within the brand ecosystem. Whether you need a riding mower or a snow blower, the financing is tailored to the specific equipment you are eyeing. Many deals include «no money down» options, which is ideal for seasonal workers who want to preserve their cash for fuel and maintenance.
Pros:- Direct manufacturer support
- Options for specialized equipment
- Streamlined application process
- Terms are subject to specific model availability
2. JetzLoan
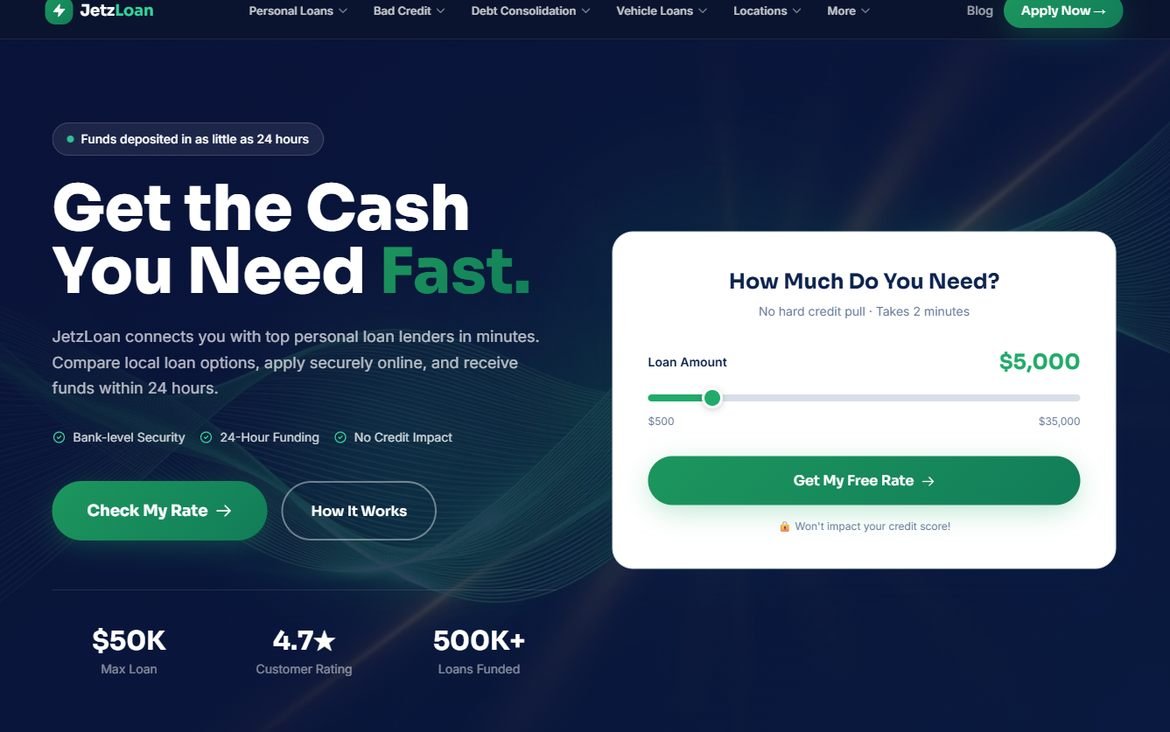
When speed is the name of the game, JetzLoan stands out. They specialize in getting funds deposited into your account in as little as 24 hours. This is a lifesaver if your current mower kicks the bucket in the middle of a busy season.
In the landscaping business, a broken mower isn’t just an inconvenience; it is a halted revenue stream. JetzLoan fills that gap by providing liquidity when traditional banks might take a week to process the paperwork. It is built for the person who needs to keep working.
They offer loans up to $35,000 and do not perform a hard credit pull during the initial check. You can see your rate without any fear of a temporary dip in your credit score. This «soft pull» technology is essential for buyers who want to shop around and compare monthly payments before committing.
Pros:- Extremely fast 24-hour funding
- No hard credit pull for initial rates
- High maximum loan limit
- Digital-first approach may lack personal interaction
3. Gravely
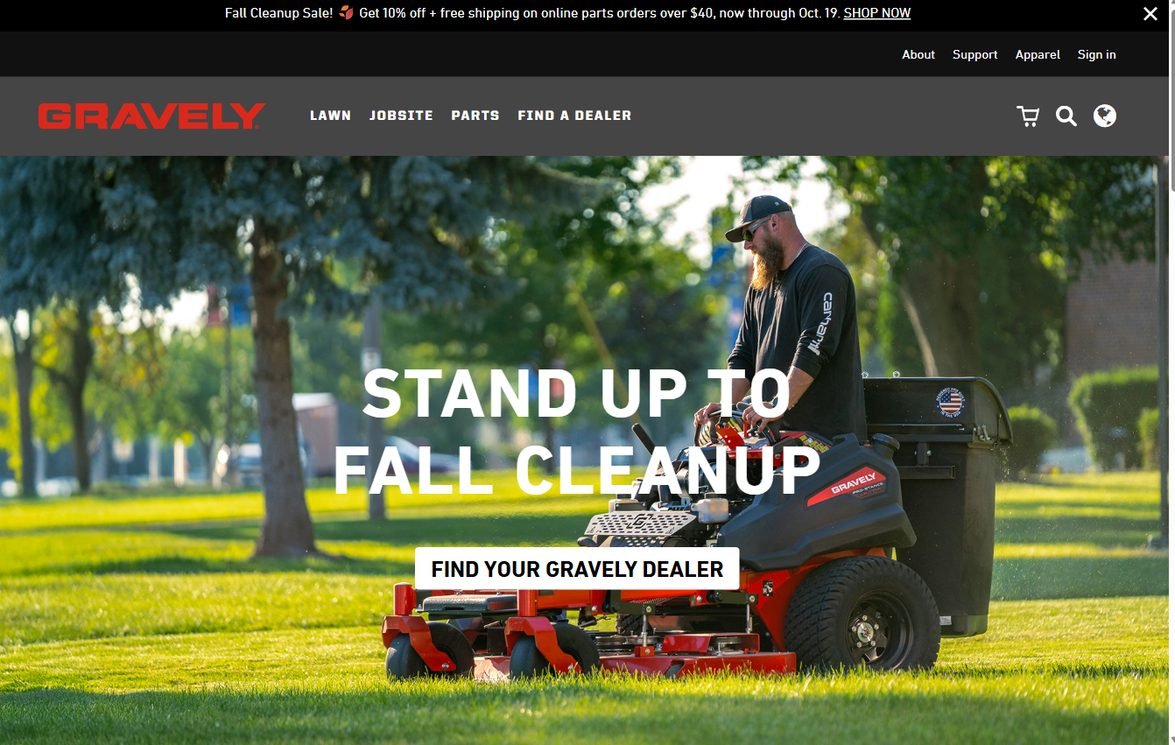
Gravely is a heavy hitter for those who treat lawn care as a professional vocation. Their financing options are built for longevity and serious business. They even offer specialized fleet pricing for pros looking to grow their entire crew’s capabilities.
Unlike consumer-grade financing, Gravely’s options often account for the higher depreciation and higher usage rates of commercial machines. They understand that a commercial mower is a tool that works much harder than a residential one.
If you are looking to outfit a fleet of commercial zero-turn mowers, Gravely provides the structural support to make that happen. They focus on the professional who needs equipment that works as hard as they do. This might include tax-advantaged leasing options or specialized business lines of credit as your client list grows.
Pros:- Excellent fleet pricing programs
- Designed for commercial-scale use
- Strong brand reputation
- Credit approval is strictly required
4. K and G Mowers
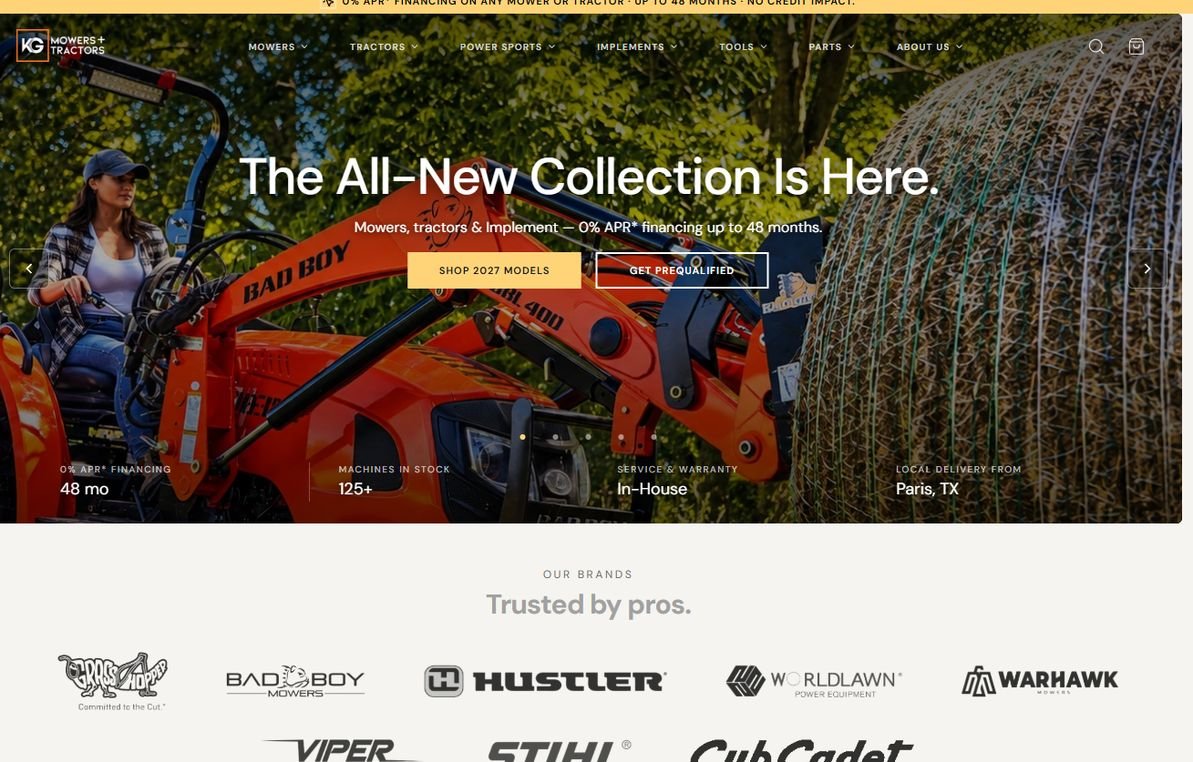
K and G Mowers provides an aggressive deal for those looking to maximize their purchasing power. They offer 0% APR financing for up to 48 months on various mowers and tractors. This is a massive advantage for someone wanting to keep their cash liquid while still getting new gear.
At 0% APR, every dollar you pay goes directly toward the principal of the machine. You aren’t being eaten up by interest charges that can add hundreds or even thousands to the total price. It is a very efficient way to use your money.
Their process is user-friendly, allowing you to get prequalified without a credit impact. Based in Paris, TX, they also provide local delivery and in-house service. This hybrid model—combining online prequalification with local, physical service—is ideal for buyers who want modern fintech convenience with the security of a brick-and-mortar business.
Pros:- 0% APR for up to 48 months
- No credit impact prequalification
- Local delivery and service available
- Physical location is localized to Texas
5. Manhattan Bank
For those who prefer the security of a traditional institution, Manhattan Bank offers a stable alternative. As an FDIC-insured entity, they provide the peace of mind that comes with working with a bank backed by the U.S. Government. This is vital for large-scale commercial purchases.
If you are seeking a high-limit business loan that requires deep scrutiny of your company’s financial history, a bank is often the right path. They offer personal and business loans for many different occasions, catering to various needs.
While it might not be as «instant» as a fintech app, the stability and professional oversight of a bank can be vital for complex financing. If you are planning to build a massive equipment warehouse or purchase multiple heavy tractors, a relationship with an established bank can provide more flexible long-term lines of credit.
Pros:- FDIC-insured security
- Personal and business loan options
- Established banking reputation
- Likely slower than instant digital lenders
6. Minute Loan Center
Minute Loan Center is the go-to for people who need money immediately and may have had a bumpy road with their credit. They focus on fast approval, even for those with fair credit, and can offer same-day deposits via direct deposit. This is perfect for emergencies.
Imagine a mower fails on a Monday and you need a new one working by Tuesday to fulfill your contracts. This is an excellent choice for that «emergency replacement» scenario. They emphasize a transparent process with no hidden fees, which helps take the stress out of a high-pressure decision.
While the interest rates might reflect the higher risk of the loan, the speed and accessibility make it a vital resource for maintaining business continuity. It is about keeping your business moving when things go wrong.
Pros:- Same-day loan disbursement
- Approvals for fair credit holders
- No hidden fees
- Interest rates may be higher for non-prime credit
7. Yanmar
Yanmar represents a global standard for heavy-duty, high-quality machinery. While they are a massive international entity, their financing is about providing a way to access world-class equipment across various regions. Their structures often reflect the high resale value of Yanmar machines.
This high resale value can make securing a loan easier through specialized agricultural or commercial lenders. They are a great choice for those who want the absolute best in engineering and a brand that supports its machinery globally.
It is a long-term investment in quality that spans continents. When you finance a Yanmar, you aren’t just buying a machine; you are investing in a piece of infrastructure that is expected to serve you for a decade or more.
Pros:- World-class machinery quality
- Global brand presence
- Highly durable equipment
- Less focus on consumer-level quick financing
The True Cost: Interest vs. Opportunity Cost
When deciding between a low-interest manufacturer deal and a high-speed digital loan, you must weigh interest costs against opportunity costs. For example, if a manufacturer offers 0% APR for 48 months, but a digital lender like JetzLoan offers a 5% interest rate but provides the money 4 days faster, which is better for you?
If those 4 days allow you to complete three landscaping jobs that generate $1,200 in profit, then the «expensive» loan actually saved you money. The speed of the capital outweighed the cost of the interest. You have to look at the bigger picture of your cash flow.
Conversely, if you are a homeowner with a large savings account, paying cash might seem like the best move to avoid interest. However, if that cash could be earning 5% in a high-yield savings account while you only pay 3% on a mower loan, you are actually losing money by paying cash. Understanding the math is the difference between a smart purchase and a financial burden.
Common Financing Pitfalls to Avoid
Before you sign any paperwork, take a moment to breathe and look at the fine print. Many people fall into the trap of only looking at the monthly payment. A low monthly payment sounds lovely, but if it comes with a massive interest rate over five years, you will end up paying for that mower twice.
Always calculate the «Total of Payments.» Multiply the monthly payment by the number of months to see the real cost. It is a simple calculation that reveals the truth behind the marketing. You need to know exactly how much cash is leaving your pocket over the life of the loan.
Always check if the lender offers a «no credit impact» prequalification. This allows you to shop around and compare different offers from companies like JetzLoan or K and G Mowers without hurting your credit score. It is like window shopping; you want to see the price before you commit to the test drive.
Watch out for the «hidden» costs that often hide in the shadows of a contract. Some lenders might charge origination fees or high late fees if you miss a single payment. If you are buying for a business, ensure the terms align with your seasonal income.
You might want to ask specifically about «seasonal payment» options. These allow you to pay more in the summer and less in the winter—a feature many commercial lenders are willing to provide for established businesses. It keeps your finances balanced when the grass isn’t growing.
Playthrough is the mechanism that separates a headline bonus from real cash. It is expressed as a simple multiple, yet the details underneath change the true figure dramatically. Two offers advertising the same number can require very different amounts of play.
How Wagering Requirements Are Calculated
A thirty five times requirement applied to bonus plus deposit is nearly twice the work of the same figure applied to bonus only, which is why that phrase deserves close reading. Players comparing terms in detail often Luckywave Casino before accepting an offer. Game weighting then adjusts everything again, since table games frequently contribute ten percent or nothing at all.
| Term | What to Check |
|---|---|
| Weighting | How much each game type contributes |
| Max bet | The stake ceiling while wagering |
| Sticky | Whether the credit is ever withdrawable |
- Ask whether the bonus is sticky or released as cash
- Track the expiry window on unmet requirements
The clearest test of any bonus is converting its multiplier into a cash turnover figure and asking whether you would voluntarily stake that much. If the answer is no, the offer is not suited to you regardless of its size. Set a deposit limit first and let the terms decide the rest.
About Post Author

