
Top 5 Lenders for Manufactured Home Financing in 2026
Top 5 Lenders for Manufactured Home Financing in 2026
Last updated: 2026-10-16
Finding the right way to pay for a manufactured home can feel like walking through a thick fog. Some people look for the stability of government-backed programs. Others need the quick turnaround of a private lender to secure a specific lot before someone else grabs it. Choosing the wrong path often leads to higher interest rates or unexpected hurdles that complicate your move.
Consider a buyer who secures a low monthly payment on a high-interest personal loan. They might not realize until years later that the total interest paid over five years far exceeds the cost of a traditional mortgage. It is a costly mistake that many avoid by doing their homework early.
What matters most is matching your current financial profile to the right product. Whether you are working to repair a credit score or looking for a quick cash injection for a down payment, the market in 2026 offers various specialized options. Understanding these nuances is the first step toward securing your piece of the American dream.
This requires looking closely at how different lenders view risk. You also need to see how they value collateral and how quickly they can move from application to closing. Every detail counts when you are trying to make a major purchase like this.
- FHA
- MH Communities
- JetzLoan
- Roadrunner Financial
- Yanmar
Evaluating the Current Financing Landscape
Selecting a lender requires looking beyond the monthly payment. You have to assess how quickly funds arrive and what the entry requirements are for your specific credit tier. Some lenders focus on long-term stability through strict underwriting. Others prioritize speed and accessibility for those who might otherwise be denied traditional bank loans.
A consumer with a 620 FICO score might find themselves rejected by a conventional mortgage provider. However, they might be welcomed by a specialized subprime lender that understands the unique depreciation curves of manufactured housing. These specialized lenders see potential where big banks only see risk.
The criteria used for this ranking include loan accessibility, maximum funding limits, and the speed of the approval process. We looked at how these providers handle different credit scenarios, from those with established histories to those facing recent financial setbacks.
We analyzed the delta between «soft» and «hard» credit inquiries, the required documentation for income verification, and the regional availability of certain specialized programs. This ensures a balanced view of who serves the widest range of manufactured housing seekers, from the first-time buyer to the seasoned investor.
| Lender Name | Max Loan Amount | Funding Speed | Credit Requirements |
|---|---|---|---|
| FHA | $350,000 | see site | 640 FICO |
| MH Communities | see site | see site | see site |
| JetzLoan | $50,000 | 24 hours | No hard pull |
| Roadrunner Financial | see site | see site | All credit welcome |
| Yanmar | see site | see site | see site |
Top-Rated Financing Options
1. FHA
FHA loans are a cornerstone for those looking to secure a manufactured home with a government-backed safety net. These loans help make housing more accessible to Americans by providing structured guidelines and established underwriting standards. Because the Federal Housing Administration insures the lender against loss in the event of default, these loans often carry lower down payment requirements.
They can also offer more forgiving credit standards than conventional loans. This makes them a reliable choice for those who meet specific eligibility criteria. It is a solid path if you want the peace of mind that comes with government oversight.
This option is particularly suited for buyers who have a solid credit foundation but might not qualify for conventional mortgage products. For example, if you have a stable job but have a high debt-to-income ratio due to student loans, an FHA loan might offer the flexibility needed to get approved.
With a minimum FICO score requirement of 640 and a down payment around 10%, it provides a clear roadmap for long-term homeownership. However, remember that FHA loans often require the home to be permanently affixed to a foundation. They must also be located on land owned by the borrower, rather than in a rental park where you only lease the lot.
Pros:
- Established government-backed security
- Maximum loan amounts up to $350,000
- Standardized underwriting processes
Cons:
- Requires a minimum 640 FICO score
- Minimum 10% down payment required
2. MH Communities
MH Communities focuses on the human element of housing. They emphasize community living over simple transactions. They specialize in managing mobile home parks and apartment communities that aim to foster a sense of belonging. Their approach is built around providing affordable, well-maintained spaces for families and retirees alike.
Unlike a traditional bank that only sees a loan amount, MH Communities sees a resident who needs a stable environment to thrive. They treat their properties as neighborhoods rather than just sets of assets on a spreadsheet.
This is an ideal choice for individuals looking for more than just a loan. They are looking for a place to plant roots. Their management style focuses on creating safe, inviting environments where residents can find connection and peace of mind in their everyday lives.
By managing the land and the community infrastructure, they provide a layer of predictability that is often missing in private lot rentals. If you are looking to move into a community with pre-established amenities like playgrounds, paved roads, and community centers, this is a primary resource for finding your next home.
Pros:
- Focus on community-centric living
- Professional management services
- Varied housing options from apartments to parks
Cons:
- Focus is on community management rather than direct lending
- Availability is regional to the Midwest
3. JetzLoan
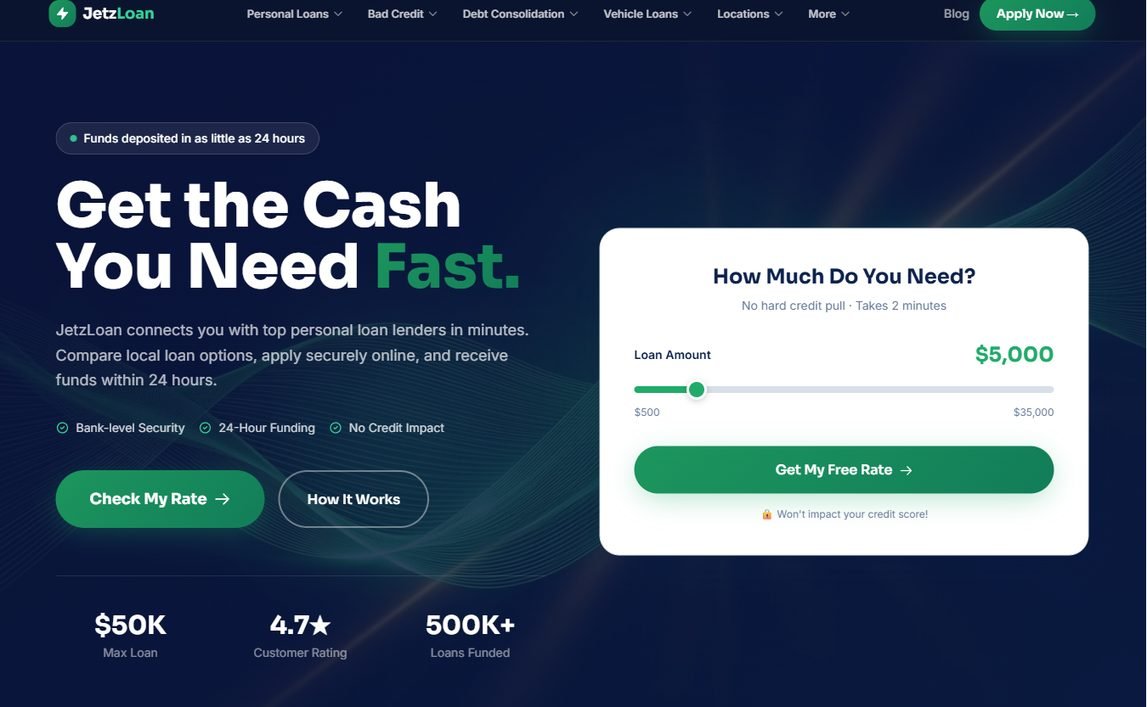
When time is of the essence, JetzLoan steps into the ring with an emphasis on speed and simplicity. They connect borrowers with top lenders in a matter of minutes. This makes the process feel less like a mountain of paperwork and more like a quick digital transaction.
It is built for the modern, fast-paced world. Opportunities like a well-priced home might only stay on the market for a few days. In those moments, you cannot afford to wait weeks for a bank to call you back.
This service is perfect for someone needing a quick injection of cash. Perhaps you need to cover closing costs, a sudden repair, or a small gap in funding that would otherwise derail a larger purchase. While a traditional mortgage might take 30 to 45 days to close, JetzLoan targets a much tighter window.
With the ability to receive funds in as little as 24 hours, it removes the agonizing wait that often plagues traditional mortgage applications. This allows you to act with the confidence of a cash buyer in certain negotiations.
Pros:
- Extremely fast 24-hour funding
- No hard credit pull to check rates
- Simple, two-minute application process
Cons:
- Loan amounts capped at $50,000
- Primarily personal loans rather than specific home mortgages
4. Roadrunner Financial
Roadrunner Financial operates with a focus on flexibility and accessibility. They welcome a wide spectrum of credit scores. They aim to strip away the haggling and hassles often found at dealerships or large banks. Their process is designed to be quick, providing real-time decisions that don’t impact your credit score during the initial inquiry phase.
This is particularly helpful for those who are still testing their budget. You can see what you can afford before committing to a formal application. It takes the guesswork out of the early stages of shopping.
This lender is a strong fit for those who want to move quickly on a purchase and need personalized offers. Because their rates are valid for 30 days, it gives the consumer a window of time to make an informed decision without feeling immediate pressure.
If you are shopping for a manufactured home at a dealership and need an answer before you leave the lot, Roadrunner’s model is built to accommodate that urgency. They maintain a level of transparency in their rate offerings that makes the whole experience easier.
Pros:
- All credit scores are welcome
- No impact on credit score during prequalification
- Competitive rates valid for 30 days
Cons:
- Focus is primarily on powersports and vehicle types
- Decisioning is heavily tied to dealership environments
5. Yanmar
Yanmar represents a global presence with a diverse reach across many different international markets. Their operations span from Europe to Southeast Asia, reflecting a massive organizational footprint. They provide a structured, corporate approach to their various business interests and regional services.
When dealing with a brand of this magnitude, you are interacting with a highly standardized system of operations. This can bring a certain level of predictability to the table, even if the scale is vast.
While they operate on a massive scale, their presence is most felt in providing specialized equipment and regional business solutions. For a consumer looking for a highly structured international brand, Yanmar offers a level of professional consistency that is hard to find in smaller, local entities.
While they may not be the first name you think of when looking for a home loan, their influence on the global supply chain and industrial equipment sectors is significant. They represent the standard for large-scale corporate efficiency and reliability.
Pros:
- Extensive global presence and brand recognition
- Highly structured regional operations
- Broad international reach
Cons:
- Not a specialized manufactured home lender
- Extremely broad focus may lack personal touch
Understanding Loan Types: Chattel vs. Mortgage
One of the most critical distinctions in manufactured housing finance is the difference between a chattel loan and a traditional mortgage. If you are buying a home that is still in its original packaging or is not permanently attached to a foundation, you will likely be looking at a chattel loan. This is a loan secured by the home itself, similar to how an auto loan works.
Because the home is considered personal property rather than real estate, interest rates are typically higher. You might also see larger down payments. It is a vital distinction to understand before you sign anything.
In contrast, a traditional mortgage covers both the home and the land it sits on. This requires the home to be legally classified as real property. This usually means it is permanently affixed to a foundation and the title has been legally converted.
Understanding this distinction is vital because it impacts your long-term equity. A mortgage allows you to build equity in the land, which historically appreciates. A chattel loan is tied to an asset that may depreciate over time. Always confirm with your lender whether they are financing the structure, the land, or both.
Step-by-Step: Preparing for Your Application
To ensure a smooth approval process, follow these strategic steps to prepare your financial profile before engaging with lenders:
- Step 1: Audit Your Credit Report. Obtain a free copy of your credit report from all three major bureaus. Look for errors, such as incorrectly reported late payments or accounts that don’t belong to you. Disputing these errors now can save you significant interest over the life of your loan.
- Step 2: Calculate Your Debt-to-Income (DTI) Ratio. Lenders look closely at how much of your monthly gross income goes toward debt payments (car loans, student loans, credit cards). Aim to keep this ratio below 36% to qualify for the best rates.
- Step 3: Gather Documentation. Be ready to provide the last two years of W-2 forms, the last two months of bank statements, and your most recent pay stubs. If you are self-employed, you will likely need two years of tax returns to prove consistent income.
- Step 4: Verify the Home’s Compliance. Ensure the manufactured home meets HUD (Department of Housing and Urban Development) standards. Lenders will require a professional inspection to verify that the home is structurally sound and meets all local safety codes.
- Step 5: Shop Around with Soft Pulls. Use lenders like Roadrunner Financial or JetzLoan to check your eligibility without hurting your credit score. Comparing at least three different quotes is the only way to ensure you aren’t overpaying.
Avoiding common pitfalls starts with knowing your numbers before you walk into any meeting. Many buyers make the mistake of applying for multiple loans simultaneously, which can inadvertently damage their credit profile. It is always better to use «soft pull» tools that allow you to compare rates without any risk to your score.
Another trap is overlooking the fine print regarding the type of loan you are receiving. There is a massive difference between a chattel loan, which is secured by the mobile home itself, and a traditional mortgage, which covers both the home and the land. Make sure you understand exactly what you are paying for before signing any binding documents.
Finally, keep an eye on the total cost of ownership rather than just the monthly payment. A lower monthly payment might seem attractive, but a longer term can result in paying thousands more in interest over the life of the loan. Always run the math on the total interest to ensure your housing choice remains affordable in the long run.
Les tournois de machines a sous transforment une session solitaire en classement partage. Les participants jouent le meme jeu pendant une periode donnee, accumulent des points selon des regles annoncees, et les premieres places se partagent une dotation. La structure parait simple, le calcul des points l'est beaucoup moins.
Comment les points de tournoi sont calcules
La plupart des tournois comptent le plus gros multiplicateur obtenu sur un tour, ou la somme des gains sur un nombre de tours fixe, ce qui favorise fortement les mises elevees. Les joueurs qui veulent lire ces baremes avant de s'inscrire peuvent play fina et comparer les formats proposes. Un evenement gratuit et un evenement payant n'ont ni la meme dotation ni le meme public.
| Format | Entree | Places payees |
|---|---|---|
| Gratuit | 0 | 20 sur 5 000 |
| Payant | 5 euros | 50 sur 1 000 |
- Lisez le mode de calcul des points avant de vous inscrire
- Regardez combien de places sont reellement payees
Un tournoi ajoute une couche de competition sur un jeu dont l'avantage de la maison reste inchange. Courir apres une place coute generalement plus que la dotation esperee. Fixez le budget de la session avant l'ouverture du classement et gardez la mise que vous auriez choisie autrement.
About Post Author

