
The 6 Best Lenders for a Personal Loan with Collateral in 2026
The 6 Best Lenders for a Personal Loan with Collateral in 2026
Last updated: 2026-10-16
Finding a lender that accepts collateral can feel like searching for a needle in a haystack when your credit score isn’t pristine. For many, using an asset as security is the golden ticket to unlocking lower interest rates and higher borrowing limits. It provides a safety net for the lender and a lifeline for the borrower.
By pledging an asset—whether it is a vehicle title, a savings account, or even professional equipment—you are effectively reducing the lender’s risk. In the eyes of a creditor, a loan without collateral is a «promise to pay,» which is high risk. A loan with collateral is a «guarantee of recovery,» which is much more attractive.
Choosing the right partner requires looking beyond just the interest rate. You must weigh the speed of funding against the flexibility of the terms. Some lenders specialize in quick cash for emergencies where the priority is immediate liquidity. Others focus on long-term stability for major life investments or equipment purchases.
For example, an emergency repair on a delivery truck requires a lender that can fund within hours. An agricultural expansion requires a lender that understands seasonal cash flow and can offer a structured repayment plan that aligns with harvest cycles.
- OneMain Financial
- Max Cash
- FastLendGo
- AgDirect
- Reprise
- Prosper
How These Lenders Were Evaluated
The selection process focused on lenders that offer specific advantages for those utilizing collateral. This includes evaluating the range of loan amounts available and the speed at which funds hit your bank account. We looked for variety, ensuring options exist for everything from small emergency gaps to large-scale agricultural financing.
We specifically scrutinized the «time-to-cash» metric. This measures the duration from the moment an application is submitted to the moment funds are available for use. Speed often determines whether a loan solves a problem or merely delays it.
Credit requirements were a major factor in this comparison. Since secured loans are often the primary route for those with less-than-perfect credit, we prioritized lenders that provide pathways for various credit profiles. Every entry was vetted to ensure their stated terms align with current market availability for 2026.
We evaluated lenders based on their willingness to look at «alternative data.» Consistent utility payments or rental history are vital for those who may have a thin credit file but possess significant tangible assets. This approach helps provide a fairer assessment of a borrower’s reliability.
| Lender | Loan Amounts | Terms/Speed | Credit Requirements |
|---|---|---|---|
| OneMain Financial | $1,500 – $30,000 | As soon as 1 hour | Accepts bad credit |
| Max Cash | $250 – $10,000+ | Minutes | See site |
| FastLendGo | See site | Quick access | Bad credit friendly |
| See site | See site | Ag-friendly terms | |
| Reprise | See site | See site | See site |
| Prosper | $2,000 – $50,000 | Fast funding | See site |
1. OneMain Financial
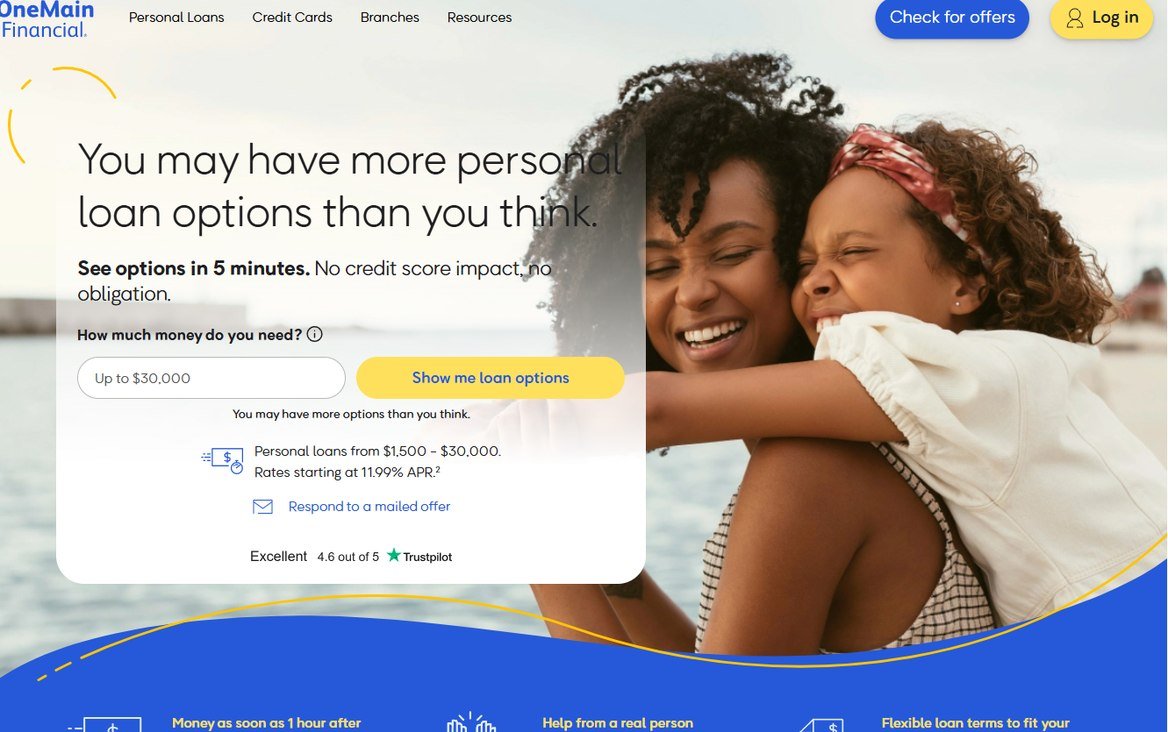
OneMain Financial stands out for those who need a human touch alongside digital convenience. With over 1,300 branches, they offer a physical presence that many online-only lenders simply cannot match. This is ideal for borrowers who want to walk into a building and speak with a real person about their options.
This physical presence is particularly valuable when dealing with complex collateral, such as a vehicle title. An in-person inspection or verification might be required to finalize the loan terms. Having a local office to visit can ease the anxiety of large financial commitments.
They cater specifically to a wide range of credit profiles, including those with bad credit. By offering secured loans, they help bridge the gap for many. If you need funds quickly, they can deliver money as soon as one hour after the loan is signed, making them a powerhouse for urgent needs.
Their ability to look at the total picture of your finances, rather than just a single credit score number, gives them a competitive edge in the secured lending market. It is a more holistic way to view a borrower’s potential.
Pros:
- Access to 1,300 physical branches for in-person support.
- Very fast funding, potentially within one hour.
- Flexible terms from 24 to 60 months.
Cons:
- Interest rates may vary significantly based on credit history.
2. Max Cash
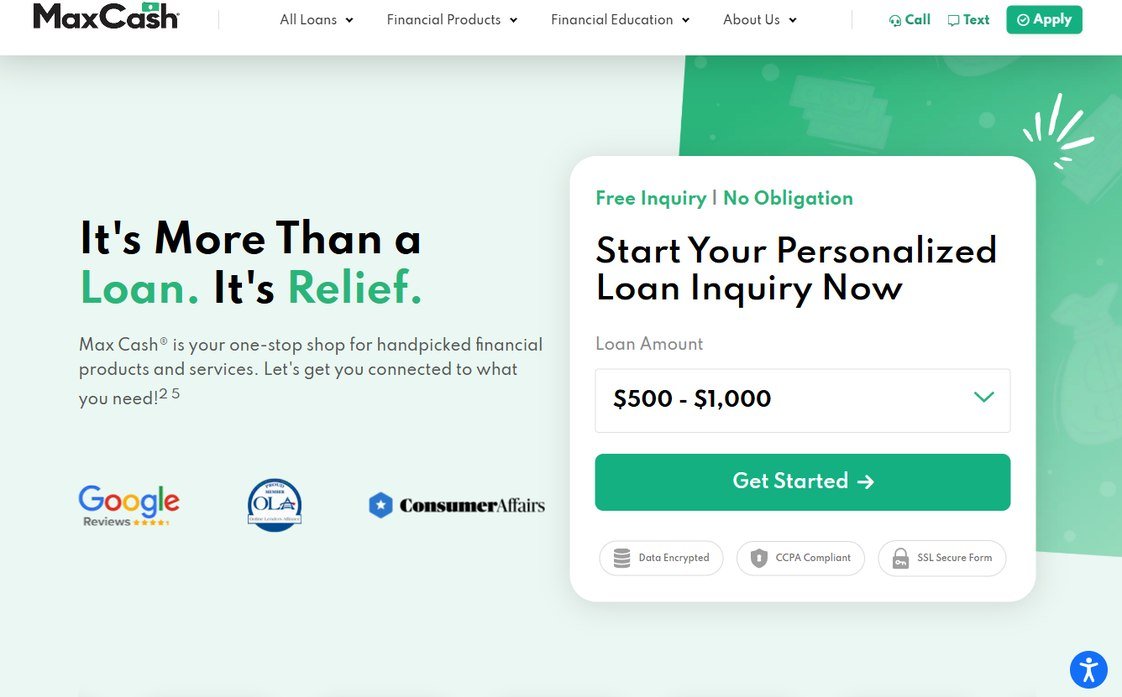
Max Cash operates as a versatile one-stop shop for various financial needs. They offer a wide spectrum of loan amounts, starting from a modest $250 all the way up to $10,000 or more. This makes them a go-to option for anyone needing a quick cash injection to cover immediate expenses.
Unexpected utility bills or a minor medical co-pay can catch anyone off guard. Because the minimum threshold is so low, they democratize access to liquidity. This is helpful for those who might not qualify for traditional bank loans due to the small size of their request.
The platform is designed for speed, aiming to get users connected to products in minutes. Whether you are looking for installment loans, title loans, or simple cash advances, they provide a streamlined digital experience. It is a high-speed option for those who cannot afford to wait for traditional banking processes.
Underwriting and fund disbursement can often take several business days at a standard bank. Max Cash skips the long wait times for those who need relief immediately.
Pros:
- Extremely low minimum loan amounts starting at $250.
- Highly efficient process for quick relief.
- Wide variety of financial products available.
Cons:
- The focus on speed may come with higher costs for short-term relief.
3. FastLendGo
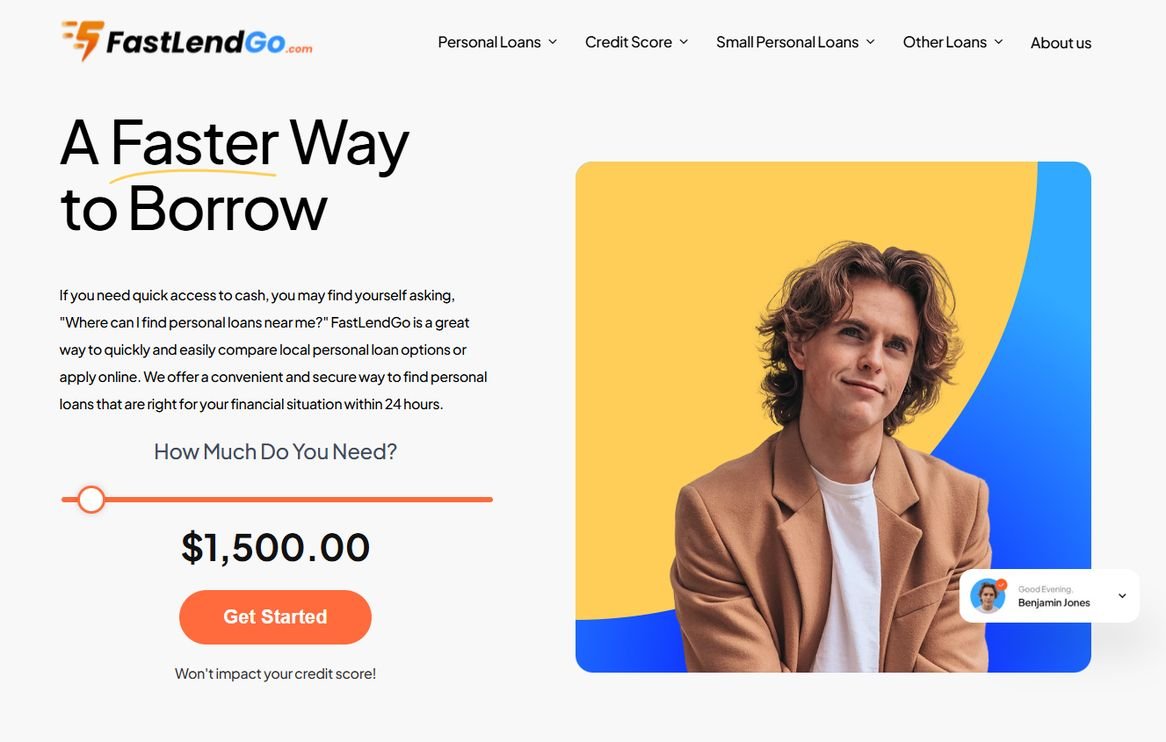
FastLendGo functions as a comprehensive bridge for those navigating the complexities of modern credit. They specialize in helping people find local personal loan options without the headache of endless searching. Their model is built around providing quick access to cash for various specific needs.
They act as a digital aggregator that sifts through localized lending criteria to find a match for the borrower’s specific situation. (fastlendgo.com) This can save a significant amount of time during stressful financial moments.
Whether you are facing an unexpected auto repair bill or need dental financing, they have a niche. They are particularly well-suited for individuals with bad credit or those who are first-time borrowers. Their ability to handle everything from small $500 loans to larger amounts makes them highly adaptable.
If your car is your primary way to get to work, their specialized focus on auto-related financing can help. You can get back on the road without the lengthy delays of a traditional credit union.
Pros:
- Specialized options for specific needs like auto or roof repair.
- Strong focus on bad credit and first-time borrowers.
- User-friendly comparison of local options.
Cons:
- Availability is limited to specific states.
4. AgDirect
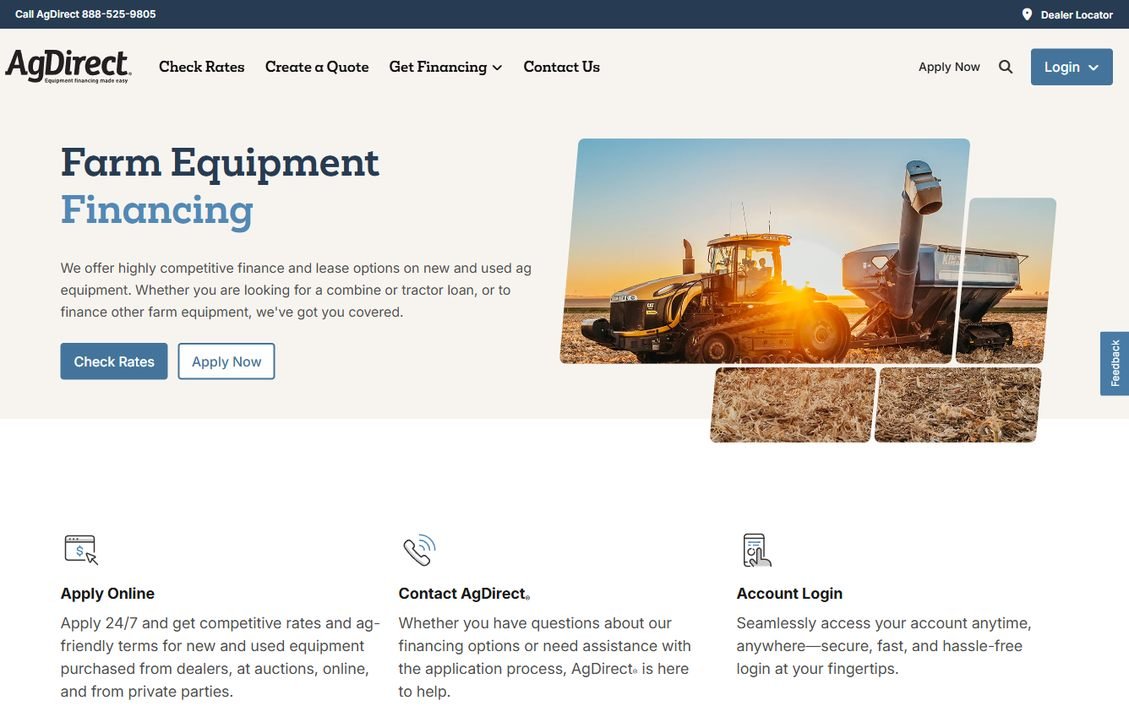
AgDirect is a specialist in a very specific niche: farm equipment financing. If you are an agricultural professional looking to upgrade your machinery, this is a highly tailored solution. They understand that farming is not a standard 9-to-5 industry.
The sector is subject to weather, seasonal commodity prices, and cyclical market shifts. This specialized knowledge allows them to offer financing and lease options for both new and used equipment, covering everything from tractors to combines.
The service is designed with the unique rhythm of farming in mind, offering ag-friendly terms. You can apply 24/7 and get competitive rates for equipment purchased from dealers, auctions, or even private parties. This flexibility is vital when a farmer finds a piece of machinery at a local auction.
You might need to move quickly to secure a deal at auction. It is a professional-grade tool for a professional-grade industry, providing the specialized underwriting necessary for heavy capital investments.
Pros:
- Highly specialized for the agricultural sector.
- Supports purchases from private parties and auctions.
- 24/7 application availability.
Cons:
- Not a general-purpose lender for non-farm needs.
5. Reprise
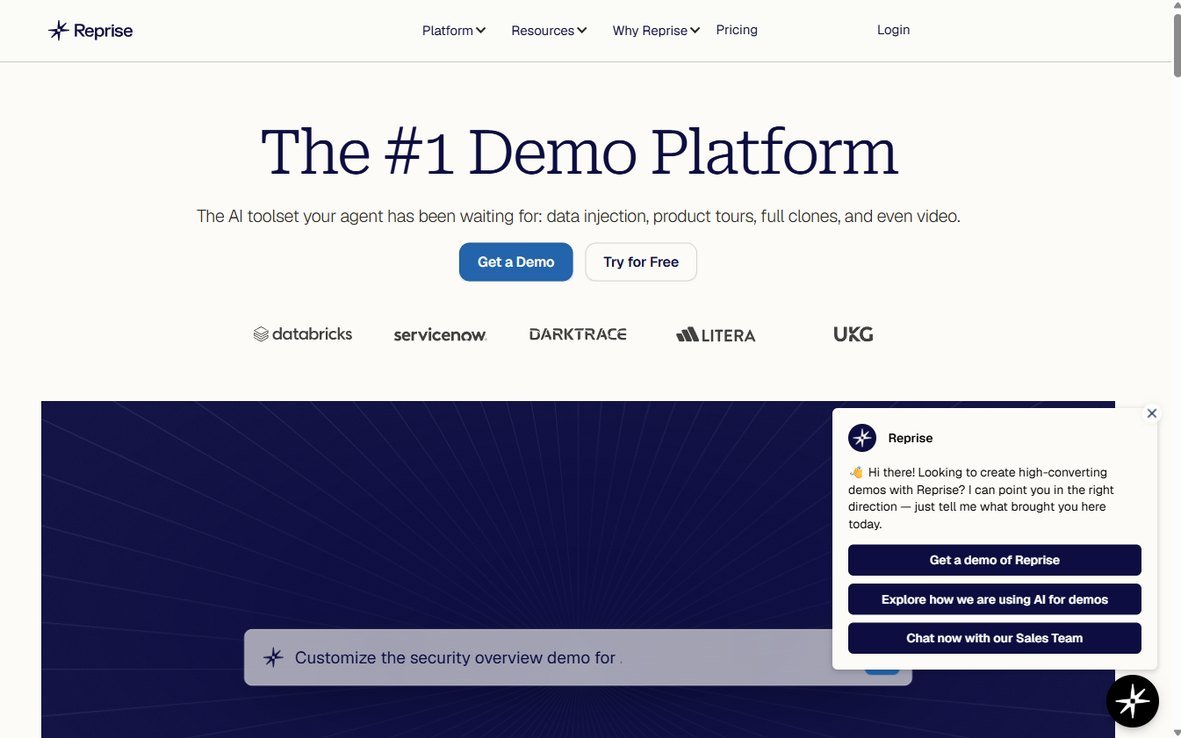
Reprise takes a completely different approach by focusing on digital interaction. While they are primarily an enterprise demo creation platform, their AI toolset is highly effective for businesses. They provide the tech to make digital demonstrations much more interactive and data-driven.
In a world where first impressions are often digital, having a polished, interactive product tour can be the difference between a closed sale and a lost lead. They offer advanced capabilities like data injection and full clones of applications.
This allows users to show live, customized data during a presentation, making the experience much more impactful. Instead of showing a static screenshot of a software interface, a salesperson can show a prospective client seeing their own actual data inside the software.
It is a sophisticated tool for companies that need their digital presence to be perfect. Their sales pitches can become undeniably realistic through these high-end digital demos.
Pros:
- Powerful AI toolset for creating high-end demos.
- Ability to inject real-time data into presentations.
- Efficient for managing complex product tours.
Cons:
- Not a personal loan lender for individual financial needs.
6. Prosper
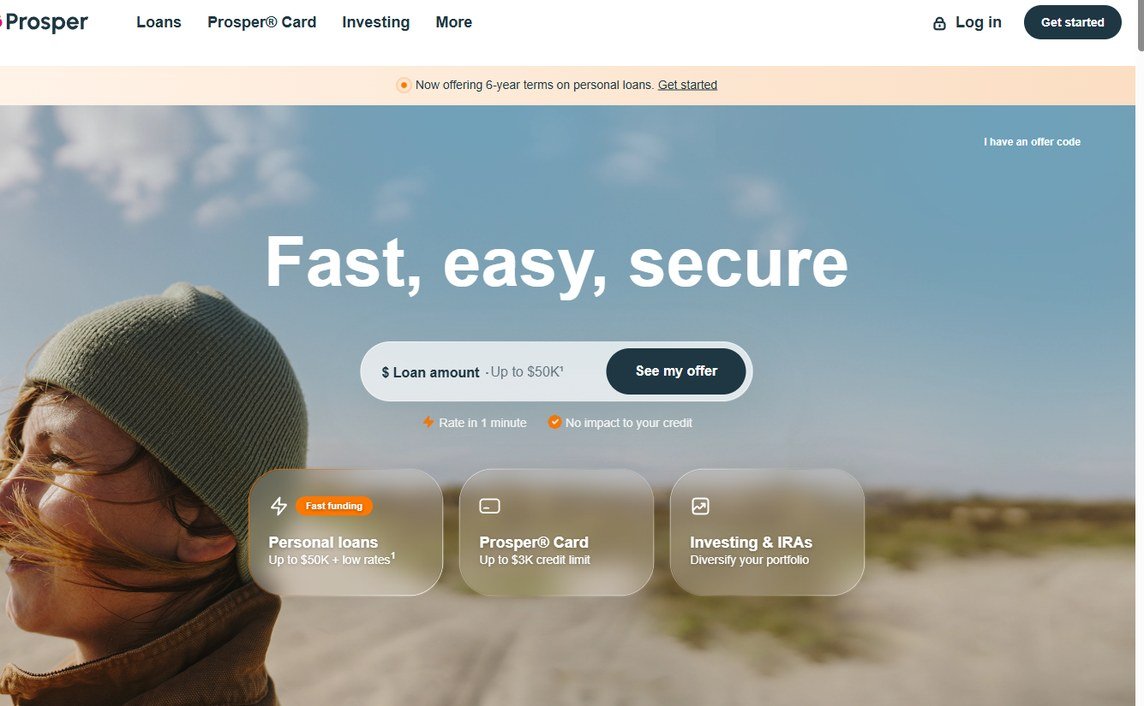
Prosper is a heavyweight in the online lending space, offering a platform that connects borrowers with lenders through a peer-to-peer (P2P) model. They provide personal loans ranging from $2,000 up to $50,000. Their reputation is backed by high ratings and a significant number of positive customer reviews.
By cutting out the traditional banking middleman, Prosper can often provide more competitive rates for those with good credit. They also offer more diverse options for those who need a different approach to borrowing.
The platform is known for being fast, easy, and secure. One of the biggest draws is the ability to check your rates in just one minute without impacting your credit score. This «soft pull» allows you to shop around and see your potential terms before making a formal commitment.
You can see interest rates and monthly payments upfront. This transparency is essential for budgeting and ensures you are not surprised by the cost of capital once the loan is finalized.
Pros:
- Significant loan amounts up to $50,000.
- No impact to credit score during the initial rate check.
- Strong reputation and high customer satisfaction.
Cons:
- The peer-to-peer model can sometimes result in different approval speeds.
How to Prepare for a Collateral-Based Loan
Before you approach a lender, you must have your documentation in perfect order. Securing a loan with an asset requires much more verification than an unsecured personal loan. Lenders will need to verify ownership, value, and condition of the collateral.
Taking these steps beforehand can shave days off your approval time. First, gather proof of ownership. This includes vehicle titles, property deeds, or purchase invoices for equipment. Second, obtain a recent appraisal or valuation.
If you are using a car as collateral, a Kelley Blue Book value or a local dealership quote is often necessary. If you are using real estate, a professional appraisal is mandatory. Third, prepare your financial statements. Even with collateral, lenders will want to see your income stability.
They need to ensure you can handle the interest payments, even if the asset is protected. A step-by-step checklist for preparation includes:
- Verify the clear title of the asset (ensure there are no existing liens).
- Take high-quality photographs of the asset to prove its current condition.
- Gather at least three months of recent bank statements.
- Prepare a detailed list of your existing monthly debts to show your debt-to-income ratio.
Understanding the Risks of Secured Lending
When you decide to use collateral to secure a loan, you are essentially making a promise backed by your property. It is a powerful way to lower your interest rates, but it comes with a significant responsibility. If you cannot meet the repayment schedule, that asset is at risk of being seized.
This process, often called repossession for vehicles or foreclosure for real estate, can have long-term impacts on your credit score and your lifestyle. Avoid the trap of borrowing more than you truly need just because the lender offers it.
It is easy to get caught up in the excitement of a large lump sum, but the monthly payments must remain manageable. Always calculate your total monthly debt obligations before signing a single document. A good rule of thumb is to ensure that your total debt payments—including this new loan—do not exceed 35-40% of your gross monthly income.
Mistakes often happen when borrowers fail to read the fine print regarding late fees and prepayment penalties. Some lenders are happy to let you pay the loan off early, which can save you thousands in interest. Others might charge you for the privilege, known as a prepayment penalty.
Always ask these questions upfront:
1. What is the exact penalty for paying this loan off early?
2. What happens if the value of my collateral drops below the loan amount?
3. Are there any hidden fees for servicing the loan or maintaining the collateral (such as required insurance)?
4. How quickly can I reclaim my title/deed once the loan is paid in full?
Return to player is a long run average, not a description of a session. Variance is the missing figure that tells you how bumpy the ride between those averages will be. It is the single statistic most players ignore and most feel the effects of.
Understanding Slot Volatility and Variance
A high volatility game may pay nothing for two hundred spins and then return a large multiple in one, while a low volatility title trickles back small amounts almost continuously. Players matching games to their bankroll often Hadesbet Casino to see variance ratings listed next to return figures. The house edge is identical in both cases, only the shape of the distribution changes.
| Volatility | Hit Frequency | Typical Top Win |
|---|---|---|
| Low | 30% | 500x |
| Medium | 22% | 2000x |
| High | 15% | 10000x |
- Check the volatility rating before the return figure
- Lower your stake when variance is high
- Expect long dry spells on big jackpot titles
No amount of variance analysis removes the built in house margin, and choosing a high volatility game is not a strategy. It is a preference about pacing. Set a figure you are content to lose, treat the swings as part of the entertainment, and leave the table when the number is reached.
About Post Author

